

Contents
Things that caught our attention
Introduction
In January, we published three reports about the development of TikTok Shop around the world. We examined the progress in Southeast Asia, the UK, and the US, as well as TikTok’s struggles with live commerce.
There is a lot of interest in the current developments of TikTok in various markets where it recently launched, among which are several European countries. These new markets can learn a lot from what TikTok Shop has already achieved in other parts of the world. We have therefore decided to do another two-part update about TikTok Shop. The information in these two reports has primarily been sourced from expert interviews with (former) TikTok Shop team members, as well as Momentum Works' recent e-Commerce in Southeast Asia report. In the first report, we will discuss the progress outside Asia, while in the second report, we will describe the developments in Southeast Asia.
In this first report, free subscribers can read the current status of TikTok Shop in various markets around the world. Paid subscribers can read the full report and will learn:
How TikTok Shop is changing its e-commerce model and how live commerce is developing.
Details about the layoffs and management changes at TikTok Shop US.
The outlook and targets for TikTok Shop.
And more …
Become a paying subscriber to unlock the full report and support our in-depth research into key China tech trends.
The information below refers to the US market, unless stated otherwise.
Ed Sander, Tech Research Analyst
P.S. The second part of the WeChat e-commerce report will be published in August.

TikTok Shop markets around the world
USA
As we described in our reports earlier this year, TikTok Shop’s performance in the US market has not been satisfactory for Bytedance, with actual sales in the US market only reaching half of the expected target.
The US market performed poorly in 2024, with a full-year target of $15.5 billion, but only US$8.6 billion (with a commission rate of 5%) was achieved, and the subsidy rate and subsidy amount reached the highest level (see ‘Subsidies’).
In 2025, the US market GMV has declined, with average daily sales decreasing from $60 million to $50 million, and the future trend is still unclear. In contrast, Temu's daily sales peaked at $138 million and Shein's at $80 million during the same period.

The US branch of TikTok Shop faces many challenges. First, the operation of content e-commerce in the US market has encountered difficulties (see ‘Development of live commerce’), and external factors such as tariffs have had a significant impact.
By June 2025, the daily sales of TikTok's e-commerce in the United States fell further to $40 million. The reasons for the decline in sales include geopolitics, tariff policy impact, internal restructuring and uncertainty in operating rights. In particular, the cancellation of the de minimis tax exemption caused the daily sales of cross-border small package business to drop sharply from $10 million at the end of April to $2 million in the beginning of May 2025. However, by adjusting the strategy, daily sales of cross-border later rebounded to between $4.5 million and $5 million.

Second, in terms of cross-cultural management, differences in thinking and cooperation between Chinese leaders and US employees also bring some challenges (see ‘Staffing and management changes’).
In addition, middle-level managers sent from China encountered adaptability problems when applying domestic e-commerce experience to cooperation with local merchants in the United States (see ‘Development of live commerce’). TikTok has sufficient natural traffic, but the effect of traffic investment is unstable. Therefore, merchants and even brands are not very willing to invest in TikTok. [2] These factors have had a significant impact on business performance.
Europe
The European market is divided into two tiers. The United Kingdom, as a first-tier market, began operations in February 2021, and by June 2025, daily sales had reached $11 million.
NielsenIQ's revealed that TikTok Shop was the country's fastest-growing e-commerce platform and third-largest online marketplace by 2024. The report highlighted that 54% of shoppers made their first purchase on TikTok Shop in 2024, while repeat customers accounted for 72% of total sales and shopped twice as often as new users. [4]
However, growth in the UK market faces challenges, with little significant change expected from the beginning of the year to the end of the year.
In the UK, TikTok Shop has launched a program for onboarding Chinese and Hong Kong businesses. On February 19, TikTok held a matchmaking meeting for leading merchants and influencer agencies in Shenzhen, at which it announced that the UK third-party POP cross-border store would officially open on February 26. 26 first-level categories were opened for entry, including beauty and skin care products, 3C products, and household items, etc. [3] [5]
In addition, a series of measures were announced to support sellers in opening up new markets. These included ‘Quick Settlement’ (TTS’s leading cross-border self-operated merchants in the UK can open a store in the UK with ‘one click’) and commission reduction from 9% to 2% within 90 days. The commission for 3C and some Beauty products is only 5%. In addition, there are policies such as co-funded free shipping plans and subsidies for high-quality products, all of which are to give merchants more profit space and attract more brands. [5]
The second-tier markets in Europe include Germany, France, Italy and Spain. Among them, Germany's daily sales in June were $300,000, France and Italy both $150,000 each, and Spain $140,000. The development of new markets, such as the Polish market, is still in its early stages and has not yet had a significant impact on the overall performance.
But in these new markets, the response to TikTok Shop’s launch has been lukewarm…
In Germany, where TikTok Shop launched in March, it was one of the main topics during one of the leading e-commerce conferences, K5 Future Retail, in June. Some brands shared their experiences on stage, which ranged from ‘we’re selling a lot’ (by a candy brand that was already very popular on TikTok before the launch of the shop) to ‘it has done nothing’ (by a cosmetics brand that received very little traffic and sales, despite TikTok Shop’s subsidies). (For those who understand German, the video of these experiences can be viewed here and here.)
Tech Buzz China’s Ed Sander shared his personal view in part of his keynote at K5: how we should adjust our expectations because TikTok Shop will both exceed and not meet them. The concerned section of his keynote can be watched in the video below.
An often-mentioned ‘TikTok Shop livestream success story’ at K5 and in press releases is Lidl in the UK, which sold a £30 pack of protein products in their livestream for £6, which would be donated to charity. Ed commented that with lots of free traffic, a low price, and a charity, it’s no surprise it sold its 3,000 packs in 18 minutes. [7]
Adoption in Germany remains sluggish. Since its March 31 debut, just 2.5% of German consumers have purchased via TikTok Shop, despite one-third having heard of it, according to data from media agency OMD. [6]
Other markets
Regarding the expansion plan in the Latin American market, the Mexican market was launched in December 2024, and large-scale investment promotion began at the end of January 2025. By May 2025, the average daily sales in the Mexican market reached $670,000. Daily sales are expected to grow to $800,000 this year.
In Mexico, the business environment is mainly composed of Chinese investors and companies that have migrated from the United States, and 95% of the supply chain depends on China. The number of local Mexican merchants accounts for only 20%-30%, and their sales account for less than 10%.
In August, TikTok Shop Mexico will open its self-operated POP model to Chinese cross-border sellers, allowing registration with Chinese company business licenses. The platform will support sellers with localised playbooks, product guidance, commission discounts, and a subsidised shipping program. [9]
The Brazilian market (68.8 million TikTok users) was launched on May 7, 2025 and reached daily sales of about $200,000 by the end of June. In this market, TTS currently only allows local business operations and has not yet started cross-border trade. Cross-border business in South America faces significant challenges, including high tariffs (up to 50%-70% for some categories) and visa issues. These factors make it difficult for top Chinese merchants to localise operations and recruit local anchors, thus hindering the rapid expansion of business.
Furthermore, Brazil's logistics infrastructure is relatively weak, logistics costs are high, and delivery time is long. [10] Still, Banco Santander, a Spanish international bank, has released a forecast report on the development prospects of TikTok Shop e-commerce in Brazil. The report predicts that by 2028, TikTok Shop's GMV in Brazil is expected to reach 25 billion to 39 billion reais ($4.5 - $7 billion), accounting for 5% to 9% of the market share. [8]
In Brazil, merchants drive business growth by using platforms such as Meikeduo and Shopee, among which Shopee's cross-border business performs exceptionally well. Some Chinese merchants have achieved good sales results on this platform and have gradually localised their sources of goods. This strategy helps overcome market entry barriers while also laying the foundation for future growth.
The primary purpose of setting up a factory in Mexico is to enter the US market rather than focusing on the local market. In contrast, due to the particularity of the Brazilian market, no company currently builds a factory specifically for that country, but uses existing resources for localised operations.
The Middle Eastern market has developed relatively slowly due to logistics and infrastructure issues. The scale of the Middle Eastern market is not as large as that of Mexico, and the situation is more complicated. TTS admits that its understanding of the Middle Eastern market is not comprehensive. With daily sales of less than $300,000, the region has been marginalised, and further investment has been suspended.
Although TikTok has expanded into emerging markets such as Mexico, Europe, and the Middle East, global sales have not risen significantly.

The transaction amount in the above data includes orders that were later returned or cancelled. After removing the returned and cancelled orders, the total amount is about 80% of the original data.
Operating methods (managed versus open platform)
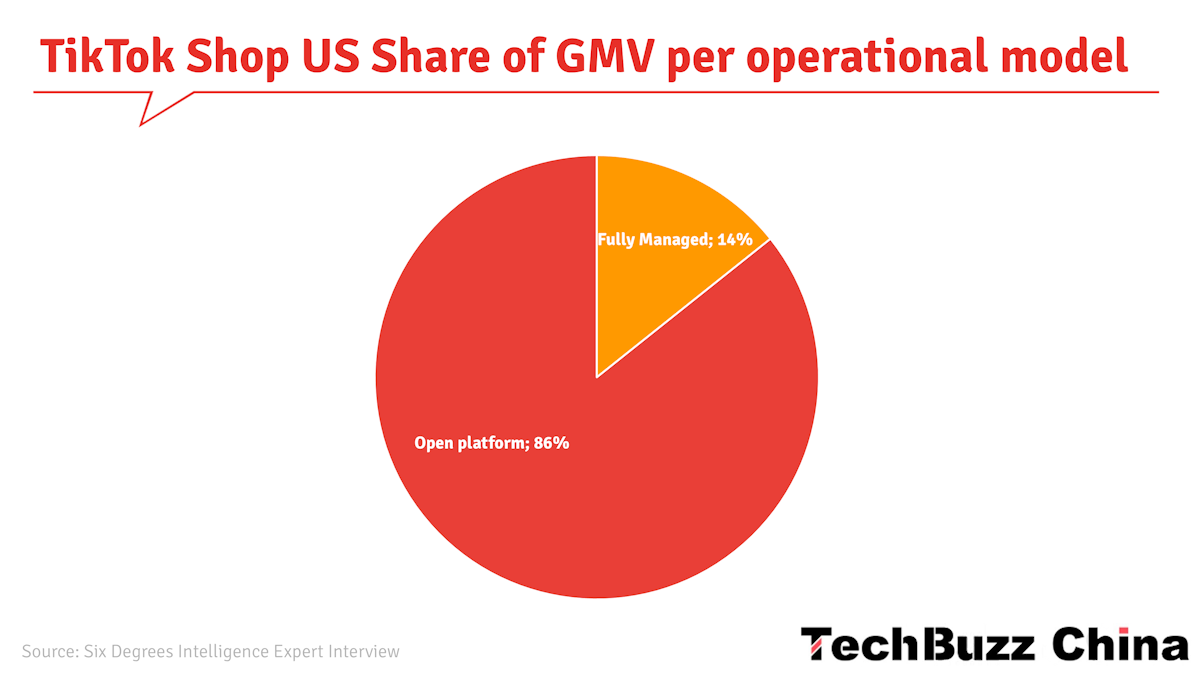
The operating methods in the United States are mainly divided into two categories: the fully managed model and the open platform model. The open platform gives third-party merchants autonomy to list goods and set prices, and the platform makes profits by charging a certain percentage of commission.
The vast majority (99%) of the managed model is fully managed, mainly through direct shipment of small cross-border packages from China. In contrast, the business volume of a semi-managed model is minimal and can be ignored. Since the cancellation of the de minimis import tax exemption, every 72 hours, the transaction volume of the fully managed model reached $6 million. In comparison, the open platform model achieved a transaction volume of $36 million.
90% of cross-border merchants in TikTok's e-commerce are from China. Since last year, the ecological involution of Douyin e-commerce in China has become increasingly severe, and it has become difficult for small and medium-sized businesses to make money. Because of this, a large number of small and medium-sized enterprises and MCN agencies have turned to TikTok e-commerce in the United States. Following this trend, TikTok’s e-commerce entry policy for merchants in the United States was also adjusted at the end of November last year. One of the most significant changes is that merchants no longer need to provide a third-party e-commerce platform experience and U.S. operating qualifications to enter TikTok's e-commerce. They can also enter by uploading business licenses from mainland China and Hong Kong. [11]
Logistics
In the Mexican and Brazilian markets, the company has adopted different logistics strategies. In Mexico, SF Express is responsible for the main transportation links, and local logistics companies complete the last-mile delivery. In Brazil, local logistics services are used throughout the process (there are no cross-border imports on TTS in Brazil).
With particular reference to the British market, TTS’s logistics distribution mainly relies on the services of Royal Mail and DHL. It used to work with Hermes, but it terminated the partnership due to its unsatisfactory performance. Local e-commerce platforms such as eBay also use similar logistics solutions, such as Royal Mail and UPS.
In terms of infrastructure services, TTS refers to the Amazon FBA model to promote the self-operation of local warehousing and logistics. At present, it adopts the certified warehouse model, with 48 certified warehouses and four official venues across the United States. In the future, TTS plans to expand the scale and gradually turn to self-operated warehouses.
In Europe, TikTok Shop has been rolling out new logistics services, including Fulfilment by TikTok (FBT) and intra-EU delivery solutions. FBT, which operates in Spain and Germany, enables local sellers to outsource fulfilment. TikTok handles storage, packing, and delivery, much like Amazon's FBA. Already active in the UK, the service supports flexible inventory storage for packages under 20kg. TikTok Shop's EU logistics offerings also aim to streamline cross-border sales by cutting customs delays and transit times. [12]
The rest of this report is available to paid subscribers.
Growth drivers
In the European and American markets, growth is primarily reflected in the increase in the number of users and a significant rise in the average order value. Notably, over the past year, the average order amount in the US and UK markets has increased substantially.
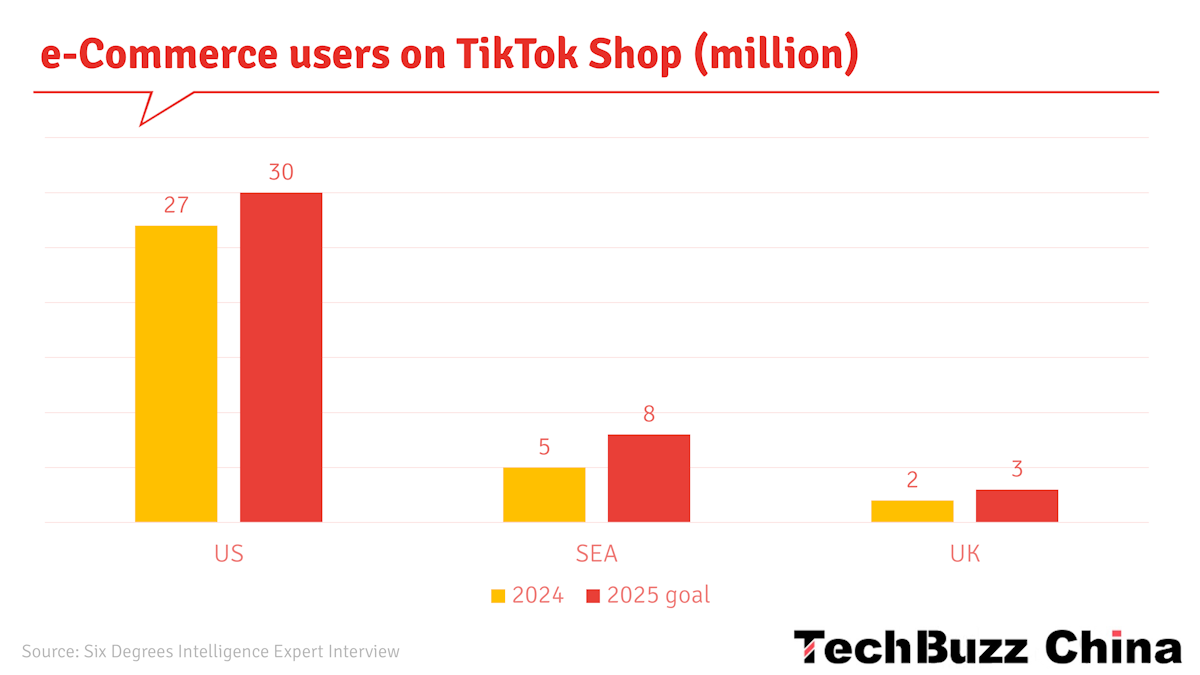
The number of TikTok Shop users in the US market has grown rapidly from a small number at the start to millions by the end of 2024. The expansion of this market mainly relies on the increase in the average order amount, while the change in purchase frequency is not significant. In the US, TikTokShop has an average order amount of $24.
It’s worth mentioning that the average return rate of TikTok e-commerce in the United States is only about 5%. In comparison, the average return rate of Douyin e-commerce in China is 40%, and the return rate of some categories, such as clothing, is even over 70%. [11]
The US market may refer to the successful model of Southeast Asia in the future, such as attracting price-sensitive users by providing small subsidies, thereby promoting the sales of high-frequency consumer goods.
To evaluate the overall growth of the market, not only should changes in the number of merchants be considered, but also the changes in the total transaction volume (GMV) of each merchant. Although the increase in the number of merchants may be the primary growth driver for TikTok Shop, the performance improvement of individual merchants cannot be ignored.
Among all merchants, only a part of them have sales. At present, TikTok Shop’s strategy is mainly focused on small merchants, and this strategy is being continuously optimised. In the US market, it has about 160,000 active merchants, while the total number of merchants in the US market is about 1.52 million. In other words, only about 10% of all registered merchants are actively selling. On the US platform, merchants who perform well can generally be divided into two types: one has highly competitive products, and the other has outstanding content production.
The merchant structure should not solely be analysed on quantity but also from other perspectives, such as contribution. The average daily sales of top merchants are usually more than $3,000 to $4,000, while the average daily sales of medium merchants are more than $800. Small and medium-sized merchants are considered long-tail merchants.
Changing e-commerce model
In the past year, the US market has undergone significant changes in its business model and has shown strong growth momentum. In the early stages of its development, TikTok launched fierce competition with competitors such as Temu by implementing a low-price strategy. Initially, the managed merchants were mainly factory-type merchants who tended to adopt a low-price sales strategy, leading to intense price competition in the market.
As time went on, around 2024, TikTok Shop started to change the business model from the initial fully managed shelf model (search-based ecommerce) to a content-centric e-commerce model, such as live broadcast and video sales. The rise of content e-commerce led to significant changes in the structure of the supply chain and merchants, and the average order amount increased accordingly. Through this content e-commerce model, goods can achieve a higher price premium, thereby increasing the value of the average order.
In the US market, local merchants and US-China joint venture merchants (a.k.a. ‘ACCU’) are of higher quality than managed (Chinese) merchants. These merchants are closer to Amazon's high-end buyer group and have stronger spending power. Local merchants and ACCU merchants have significant advantages in brand image and market share, which further promotes the expansion of the US market. This change in merchant structure, combined with the transformation of the business model, effectively increased the average order value and market share.
Content e-commerce and interest e-commerce cover two forms: live broadcast and short video, but the two are not simply additive. TikTok sees that the market share of traditional shelf e-commerce is decreasing, while the proportion of live broadcast e-commerce is gradually increasing. In the face of this trend, a comprehensive growth strategy has become crucial, including attracting new users, increasing the conversion rate and average order value of new users, and improving the repeat purchase behaviour of existing users. These changes have not only affected the platform's operating strategy but also profoundly changed users' shopping behaviour.
Still, the content e-commerce model faces some unique challenges and risks compared to traditional e-commerce. First, content e-commerce requires more labour costs, especially in positions such as operations and anchors (livestream hosts). Under this model, large fluctuations in the number of viewers may make it difficult for merchants to recover the team's investment costs. In addition, the instability of income may force merchants to stop operations after a while.
Most merchants operating on platforms such as TikTok are traders, who are at a disadvantage in price competitiveness compared to Shein and Temu, which directly connect with factories. Another challenge is that, while the number of users and AOV increase, TikTok’s performance in improving the user's re-purchase is insufficient, as it lacks sharing rewards and secondary discounts. Compared with Temu's multiple improvements in user experience, TikTok may require a lot of subsidies and a longer time to make improvements. These factors may have a significant impact on the long-term operation and profitability of merchants.
Development of live commerce
The development trends of live commerce in markets around the world show significant differences.
In China, on Douyin, the share of live commerce in sales is 70%. On TikTok Shop, the proportion of live e-commerce in various countries has increased from 2%-4% to about 20%, while the proportion of individual anchors in live e-commerce has also increased from 10%-13% to about 35%. However, as we have seen in our earlier reports, even in the Southeast Asian market, the share of live commerce in TTS GMV is still lower (40%) than that of traditional shelf e-commerce and short video e-commerce.
In 2024, only four livestreaming sessions in the US have surpassed $1 million in GMV. Amongst which the top one generated less than half of the GMV compared to the top session in Vietnam. [23]
In the UK and the US, the penetration rate of live commerce is relatively low, with the US slightly higher than the UK. Live e-commerce in the US market now accounts for nearly 20%, short video e-commerce accounts for about 45%, and the rest is made up of traditional shelf e-commerce (search-based). The UK market presents a different pattern, with live and short video e-commerce each accounting for 35%, and the rest is occupied by traditional shelf e-commerce. These data reflect the unique characteristics and trends of various markets in the development of live e-commerce.
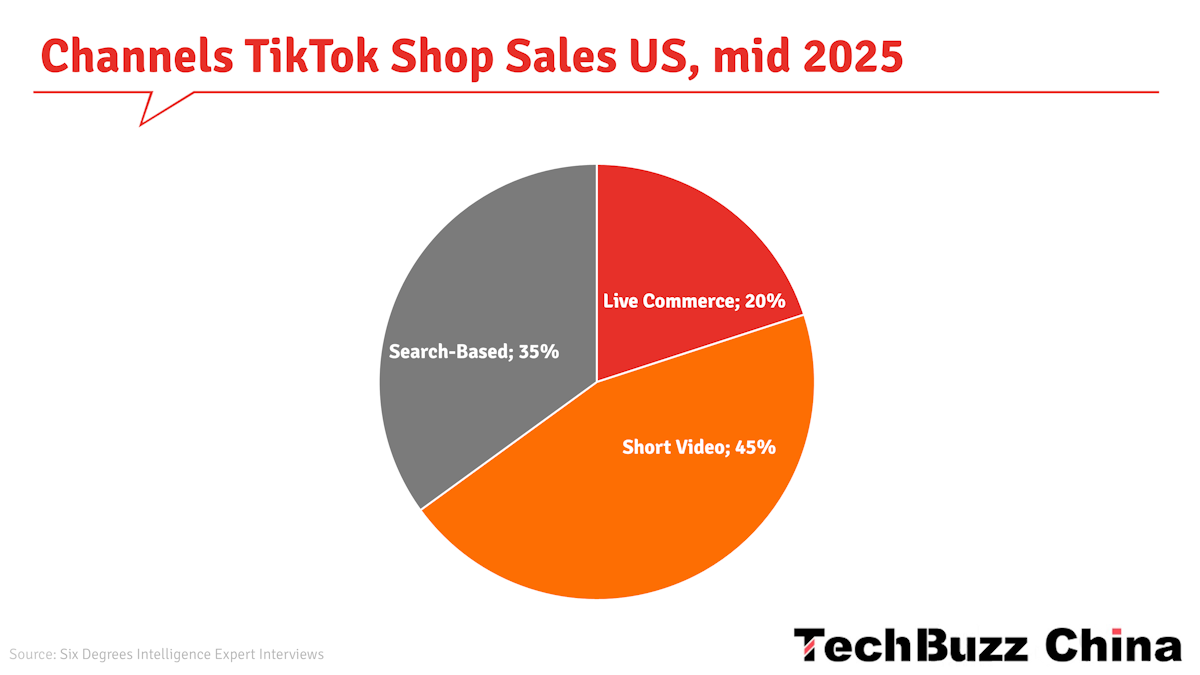
TikTok expects the proportion of live e-commerce to increase, while the proportion of traditional e-commerce may decrease. The specific growth rate has not yet been determined.
Despite the improvements in the share of live commerce in its GMV, TikTok Shop is still facing challenges in the UK: [5]
Consumers prefer offline consumption and shelf (search-based) e-commerce platforms, and have high requirements for product quality. But TikTok thinks there is progress. According to data from Retail Economics, more than half of British users have experience in social media shopping, of which TikTok accounts for 44%. However, to cover a broader range of people and age groups, merchants and platforms must continue to excel in content production and consumer experience improvement.
Content production is not suitable for the local environment. Direct hard promotion of products may yield average exposure and conversion effects, which require sellers to enhance their local influencer operation capabilities, content production, and delivery capabilities.
Competition from other platforms, especially Temu and Shein.
The main challenges faced by content e-commerce in the US market are concentrated in the supply chain and content creation, rather than policy risks. In contrast, China's supply chain has obvious advantages in product variety and price. However, China's top merchants have encountered difficulties in expanding into the US market, mainly due to restrictions on visa policies and localisation requirements. Meanwhile, American consumers still have a limited understanding of live e-commerce and often confuse it with traditional TV shopping.
Challenges in algorithm accuracy
Content e-commerce platforms such as TikTok face challenges in traffic distribution and algorithm accuracy when implementing the ‘goods find people’ model, which aims to serve users content about products that match their personal interests.
TikTok Shop faces several significant challenges in terms of push accuracy and traffic distribution. First, the accuracy of live broadcast push directly impacts key e-commerce indicators, such as conversion rate and GPM. This means that if the push is not accurate enough, it may lead to poor performance of these key indicators.
Second, if the performance of the live broadcast room is lower than the platform's average, the system may misjudge it as inefficient, resulting in traffic interruption. This situation can have a serious impact on merchants' businesses.
The inaccuracy of TikTok's e-commerce algorithm is mainly due to the lack of user purchase data. Due to the low frequency of user purchases, it is difficult for the platform to accurately portray user portraits, which directly affects the accurate grasp of user interests and needs. Especially in the US market, users shop less frequently on TikTok than on other platforms such as Temu and Amazon, which affects the accuracy of user portraits. This lack of data makes it difficult for the platform to predict user behaviour and preferences accurately, leading to mismatched recommended content. For example, the system may guide users interested in shoes to the live broadcast room of accessories or garbage bags, which will obviously affect the purchase conversion rate.
This lack of accuracy is echoed by a merchant who shared how advertising for Amazon stores generated on TikTok Shop is not as effective as traffic bought on Amazon itself. “According to our analysis, the return on internal advertising on the Amazon platform is slightly higher than directing traffic to Amazon products through TikTok. Specifically, the purchase rate of visitors directed from TikTok is 10%-15% lower than that of Amazon's own traffic, mainly because the positioning of TikTok's user groups is not accurate enough. However, due to TikTok's lower customer acquisition cost, its return on investment is still 5%-10% lower than Amazon.”
In addition, many merchants have reported that the traffic of TikTok live broadcasts fluctuated wildly, which posed a challenge to the continued development of the business. The instability of traffic makes it difficult for merchants to formulate long-term strategies and also affects their confidence in investing in the platform. These challenges combined not only affect the business performance of individual merchants, but also pose an obstacle to the overall development of TikTok Shop.
Challenges with anchors
In cross-cultural live streaming sales, the background of the anchor has a significant impact on the sales effect. Due to language and cultural differences, Chinese anchors have not performed well in the US market, a situation similar to the performance of African anchors in the Chinese market. When the same product is sold by anchors with different backgrounds, the price and conversion rate will be significantly different, and may even differ by as much as five times. Although excellent English anchors can be cultivated in Chinese cities such as Hangzhou, Guangzhou, and Shenzhen, the chance of success is very low.
In addition, the relationship between top anchors and companies is unstable, and the loss of anchors may lead to interruptions in the live streaming business. On the TikTok Shop, there are significant differences in the frequency and duration of live streaming between anchors with Chinese and non-Chinese backgrounds. Chinese anchors usually have to livestream 30 days a month for at least 5 hours a day to meet the standards. In contrast, non-Chinese anchors may go live for less than 1 hour per month, and the frequency of live streaming is unstable. These differences undoubtedly bring unique challenges and opportunities to cross-cultural live streaming sales.
TTS is actively promoting the talent business. To improve the efficiency of cooperation between merchants and influencers, TTS plans to establish an official live broadcast base in the United States as a centre for product selection. This will allow influencers to live broadcast directly from the base, thereby solving the problem of long sample delivery time and inconsistency between samples and pictures.
TTS’s goal is to build 11 live broadcast bases, but considering the actual situation, it is expected that only about six may be completed. Through these bases, it will provide offline support and cultivate top talent to set an example for the industry. This should not only enhance the confidence of small and medium-sized influencers and merchants but also reduce the trust barriers of consumers. Ultimately, TTS hopes that these efforts will promote China's white-label industry to an international level and significantly improve overall sales efficiency.
Staffing and management changes
In March, Marketplace Pulse [22] reported that TikTok was aggressively recruiting talent, with over 4,400 open positions globally. More than a quarter of these openings were for TikTok Shop roles, and more than half of the total openings were in North America. But despite these job openings, various media have in the past months reported that TikTok has carried out at least three rounds of layoffs of TikTok Shop staff since April.
In February, e-commerce head Bob Kang (Kang Zeyu) singled out the US team as underperforming. That same month, the company intensified its five-day, eight-hour-per-day return-to-office requirements for US e-commerce staff. In March, many employees received low performance review scores and were laid off. Others were suffering from burnout signs under the increasing pressure. TikTok has been offering some team members a choice to take part in a performance-improvement plan (PIP) or exit with severance via a mutual separation agreement. PIPs, which often must be completed within 30 days, were nearly impossible to accomplish and would result in termination. [13]
Business Insider has quoted a TikTok Shop US employee as saying: "Chinese leadership are just so disconnected from the Western-based e-commerce customer. They were setting revenue expectations based on their experience with Douyin and China in a very different e-commerce market." Bytedance is disappointed in the return on the investments it has put into TikTok Shop US. According to The Information, it invested $500 million in the launch year alone. The US e-commerce team also faces higher expectations than other markets, such as Southeast Asia or the UK, primarily because operating there is more expensive. [13]
In February, TikTok downsized its Trust and Safety team. In April, TikTok laid off several U.S. e-commerce staff as part of a broader overhaul of its E-commerce Governance and Experience (GNE) team, which oversees merchant compliance, product listings, and IP protection. [14]
In April, TTS US also reshuffled its management. Nico Le Bourgeois, head of US operations for TikTok Shop, was moved under Mu Qing, a former e-commerce VP for TikTok's Chinese sister app Douyin. Le Bourgeois would no longer report directly to Bob Kang and would focus on local US merchants. Mu Qing, who recently took over control of other central US Shop teams like creator and agency partnerships, now also oversees US operations. [15]
On May 21st, Mu Qing instructed employees via email to work from home. Some employees would be notified that they had been laid off. [16]
In May, a disgruntled former TTS employee wrote a long article, which we summarised here. It’s a collection of cultural clashes, chaotic work environments, inefficiency due to the compliance requirements of Project Texas, constantly changing KPIs, and marginalisation under new leadership. According to Technode, TikTok Shop’s US team has seen over 100 departures in a context of leadership confusion and a tense work environment. [17]
Besides Mu Qing, six other China-based executives were appointed to lead TikTok Shop’s US operations. Seattle meetings, once conducted in English, increasingly use Mandarin, with internal communications in Chinese requiring translation for English-speaking staff. [17]
TikTok Shop faces a series of internal challenges and organisational problems during the process of international expansion. First, its overseas team faces organisational instability, frequent changes, and conflicts in management concepts. There are multiple factions within the company, with members coming from companies with different backgrounds, such as ByteDance, Alibaba, and Amazon. Meanwhile, the layoffs from March to April 2025 led to internal instability and affected employee motivation.
In addition, due to uncertainty about TikTok's future operations in the United States, some key employees have chosen to leave, with some even joining competitors such as YouTube and Amazon. These factors have had a significant impact on TikTok's e-commerce business performance and its future development in the United States.
There are significant differences in work engagement between American and Chinese employees. This difference has an important impact on multinational companies' human resource strategies and employee retention plans. Managing employees with non-Chinese backgrounds is often more complicated for Chinese companies, as they tend to be more freedom-seeking and are more likely to leave or start their own business after gaining short-term benefits. Therefore, companies like Bytedance need to adjust their management methods based on these cultural differences to better adapt to the needs and expectations of employees in different countries.
In addition, the scarcity of promotion opportunities within TikTok has led to increasingly fierce competition between factions, making the organisational environment more complex. Due to the existence of multiple factions and frequent adjustments to strategies in different markets, TikTok's organisational efficiency has declined, and the level of confusion has increased. These internal challenges may affect the development and competitiveness of TikTok e-commerce in the global market, as companies that want to succeed in the international market must be able to achieve results quickly.
Employee salaries are still one of the main expenses of the company. Although TikTok has taken strict data isolation measures (Project Texas), this has not affected the efficiency of algorithm recommendations. However, due to the implementation of the USDF framework, the time for the Chinese operations team to obtain data reports has increased significantly, from the fastest 5 minutes and the slowest 1 day to possibly a week. In addition, the quality of data has also declined, which has seriously affected the efficiency of decision-making.
Meanwhile, TikTok is also recruiting staff for ‘TTLS’ (TikTok Local Service) in Seattle, Los Angeles and New York, showing that the company is preparing for the launch of a local services business that it also launched in Thailand and Indonesia and has been quite successful in Douyin.
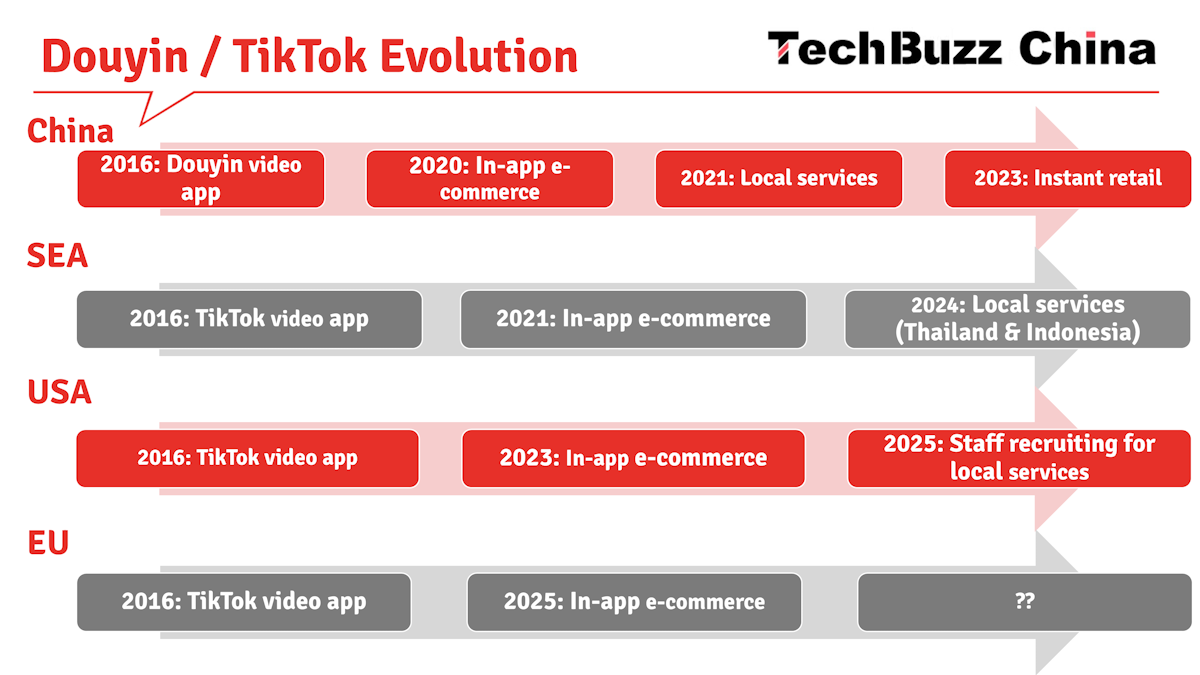
Meanwhile, in Europe, TTS is recruiting a project manager to spearhead strategy and operations for its resale category across the EU, signalling a strong push into the fast-growing circular economy sector. [18]
Product categories
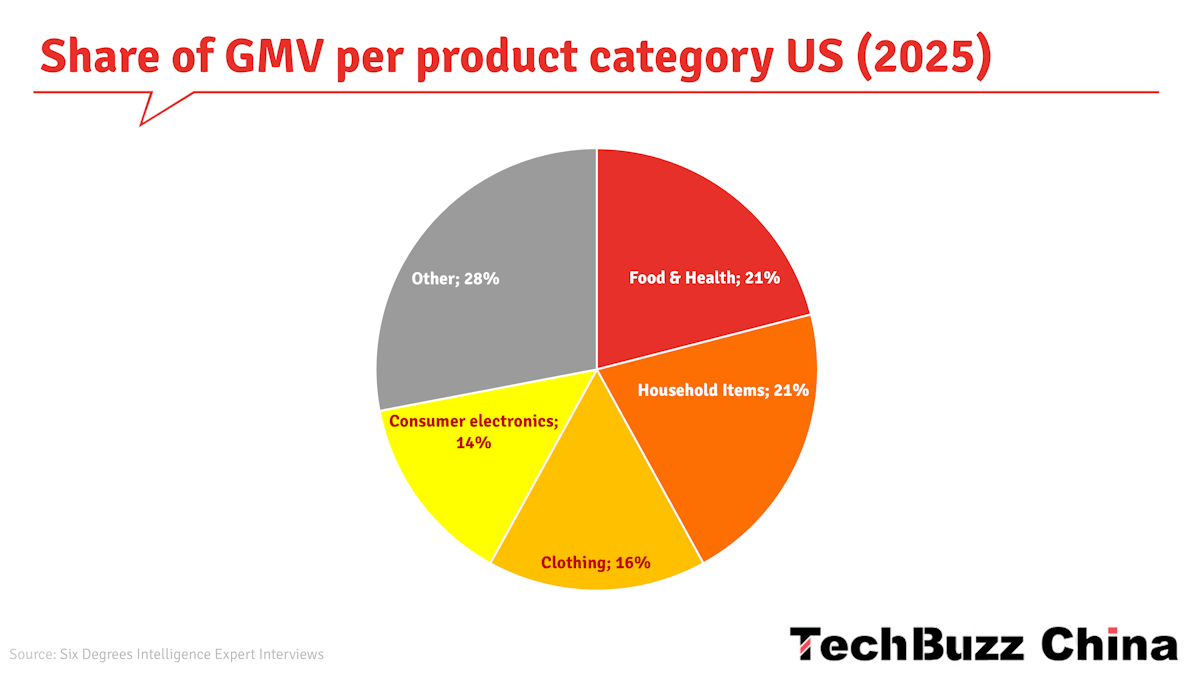
The distribution of product categories in the US market is significantly different from that in other regions. Food and health products dominate the US market, with a share of about 21%. Household items are equally important, also accounting for about 21% of the market share. Clothing products follow closely behind, accounting for about 16%, while consumer electronics account for about 14% of the market.
TTS plans to expand into new categories by leveraging the advantages of content e-commerce, especially those that do not perform well in traditional e-commerce, such as non-standard products and standard products with a large number of SKUs, such as women's clothing. Jewellery products are very suitable for sales through live broadcasts due to their ‘unique’ and ‘what you see is what you get’ characteristics.
Subsidies
TTS provides subsidies in three ways: reducing product prices, subsidising logistics costs, and providing commercial traffic support. TikTok Shop’s subsidy ratio has been high in recent years, but the specific figures have not been disclosed to the public. This subsidy strategy has had an essential impact on the company's business development and market competitiveness, helping it maintain a competitive advantage in different markets.
In the UK, in mid-2024, TikTok launched a series of significant incentive policies called the ‘Million Pound Club’ to provide strong platform-side support for merchants to encourage new British sellers to join. Under the ‘Million Pound Club’ plan, new merchants in the UK enjoy benefits including: zero commission rate for up to 90 days (reducing sales costs), free use of TikTok Shop's ‘Fulfillment By TikTok Shop’ services (reducing logistics burden); and ‘exclusive operational support for high-potential merchants’ (support in cold start sales, operational training, after-sales fulfillment, and platform marketing activities). According to reports, by the end of 2024, the number of merchants on TikTok Shop UK had exceeded 200,000, doubling in just one year. [5]
In Mexico, TikTok Shop offers free shipping throughout Mexico and discounts of up to 50% on first purchases. TikTok Shop’s commission for sellers is currently 6%, well below Shein’s 16% and comparable to AliExpress’s 5% to 8%. [20]
The current subsidy ratio is comparable to the average level of last year, especially in the US market. The subsidy rate is calculated based on the percentage of gross merchandise volume (GMV) and is directly subtracted from the consumer’s payment.
In the first half of 2025, the overall subsidy rate in the U.S. market was about 25%, which included direct subsidies for goods and subsidies for logistics costs. However, this subsidy rate does not include marketing expenses made by the platform to attract new users, such as advertising. In the U.S. market, TTS’s platform commission rate is 5%, while the transaction subsidy rate is 25%, resulting in a business loss rate of about 20%.
The strategy of relying on high marketing budgets to attract US user traffic in the past has proved to be unsustainable, and users are not loyal and price-sensitive. Once subsidies are reduced or stopped, users are easily lost. These challenges and difficulties have undoubtedly hurt the business performance and development prospects of TikTok Shop in the US.
In the US, TikTok Shop has started charging more merchants for getting views to their videos, ending the period of free traffic. Free shipping subsidies have also been scaled back. [19]
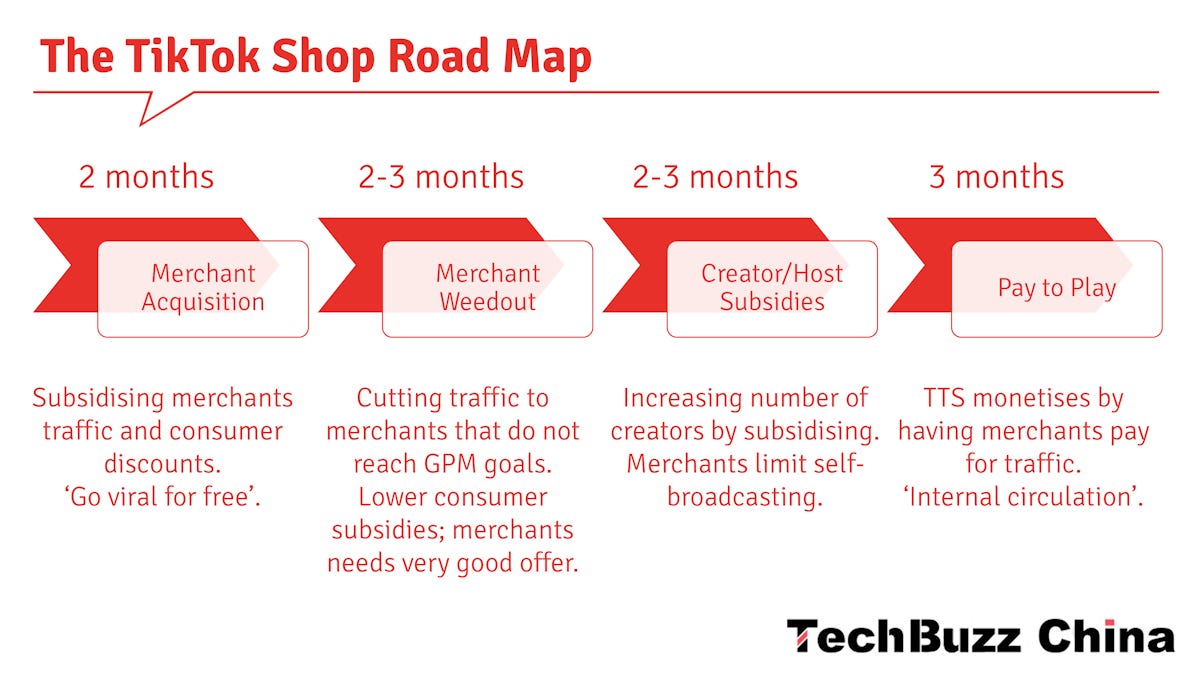
Regarding the trend of subsidy changes, it is expected that the total subsidy this year will be lower than the current monthly subsidy level, and the subsidy rate for the whole year may decline. Subsidies are usually adjusted according to specific circumstances, and there is no fixed adjustment time, but it may be done every six months. If the US market lacks momentum, funds may flow more to Southeast Asia or other emerging markets to achieve relevant goals.
Outlook
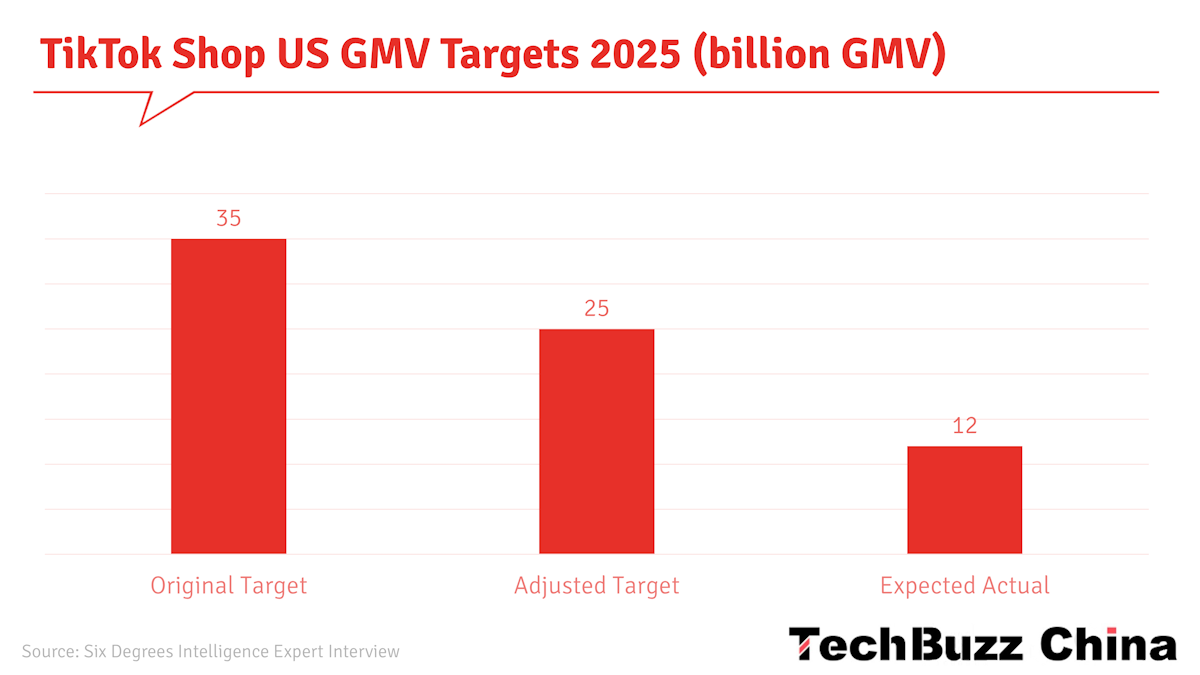
With the average daily GMV in the US market decreasing to $50 million, the annual GMV target has been lowered from $35 billion (four times its 2024 GMV!) to $25 billion, and the actual completion is expected to be far lower than this adjusted target. TTS expects full-year sales in the U.S. market to reach $12 billion by 2025, an increase of $3.4 billion compared to 2024. That’s a 40% increase, not the 400% of the original target.
During the period of 2024-2025, the subsidy rate will remain at about 25%, and new losses will mainly come from 25% of the $3.4 billion GMV increase. The US market will continue to implement subsidy policies in the future. Simply pursuing one-time user acquisition without paying attention to repurchase is unlikely to bring long-term benefits, so continuous subsidies are needed to maintain user loyalty. The company also needs to increase subsidies during sales peaks such as "Black Friday", Amazon Prime Day and Christmas, to maintain brand image and market position. Although this strategy will increase costs in the short term, TikTok considers it crucial to increase long-term market share.
Revenue goals
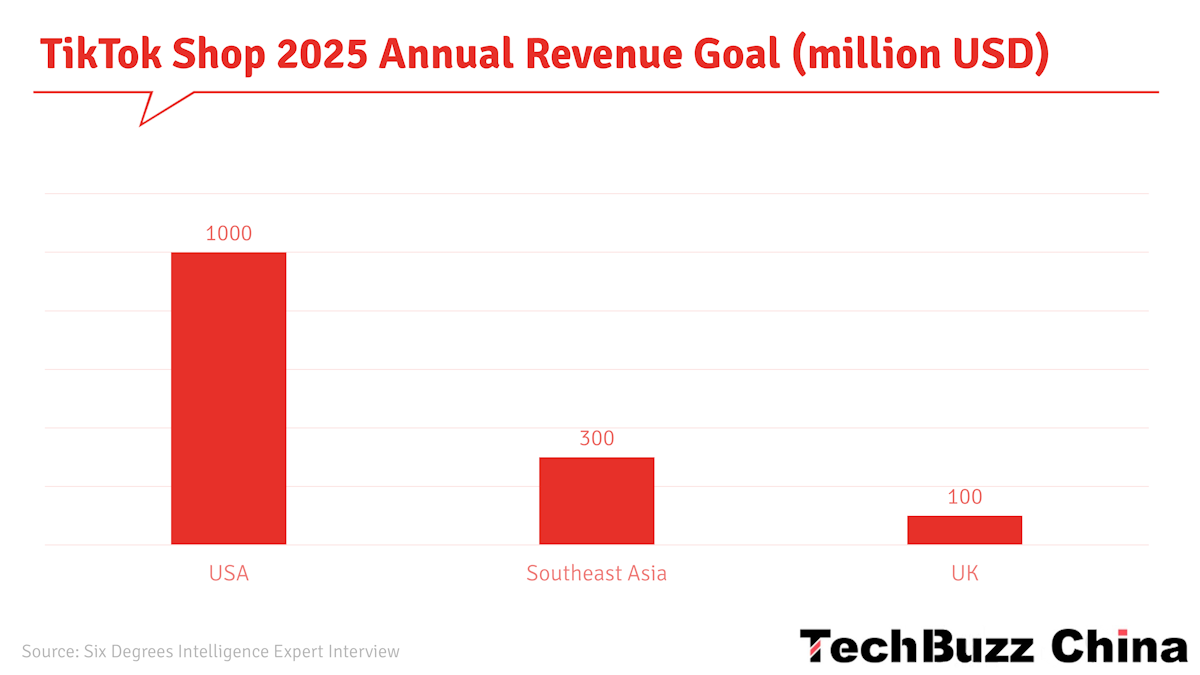
Although the global goal for 2025 has not yet been clarified, each market has set its own goals for revenue. The UK's goal is $100 million per year, Southeast Asia's is $300 million, and the US has set a goal of $1 billion. However, this goal in the United States is considered too optimistic, and the actual completion amount may be far less than $1 billion. If a 5% commission rate is applied to the expected annual GMV of $12 billion, it would be $600 million.
As for the markets launched in 2025, the Mexican market is expected to have an average daily revenue of approximately $10,000 by the end of the year, which would largely fill the existing gap in the US market. The total average daily revenue for the German, French, Spanish, and Italian markets is expected to be around $20,000.
Considering the current performance and future goals of these markets, the company needs to develop a targeted growth strategy. Specifically, for the US market, it is necessary to evaluate the feasibility of the $1 billion goal and consider the measures required to achieve this ambitious target. This may necessitate an in-depth analysis of market potential, the competitive environment, and the company's resources and capabilities to develop a practical strategy.
Although TikTok expects to achieve its goals during the peak promotion period at the end of the year, the overall data for the whole year needs to be adjusted downward. It needs to pay special attention to the overall growth expectations and must study the global situation in the first quarter in detail.
Market expansions
The company's current focus markets are the UK, the US, and Southeast Asia, excluding other emerging markets such as the Middle East, Spain, Mexico, and Brazil. However, Brazil is considered the most promising emerging market. The company has high hopes for the Brazilian market and expects to focus on developing it in the second half of the year, with potential results by the end of 2025.
Regarding the international market expansion strategy, TTS is currently facing both challenges and opportunities. Brazil's gaming and electronic policies change frequently, and their impact remains unclear and difficult to assess.
In terms of business operations, TTS has no plans to expand to other South American or Central American countries for the time being, and its business focus remains on the major countries that have already been developed.
Given the unsatisfactory performance in the Middle East, TTS will not increase investment in the region for at least the following year.
In Europe, TTS already has operations in Germany, France, Italy, Spain and the United Kingdom. It expects the Polish market to open in the second half of 2025.
TikTok Shop launched in Japan at the end of June. The number of monthly active users of TikTok in Japan has exceeded 22 million, with a large number of young users, of whom 70% are users aged 18-34. User stickiness is also very strong, with an average daily usage time of more than 60 minutes. [10]
Looking ahead, TikTok Shop plans to expand into Pakistan, the Netherlands, Belgium, Sweden, and Poland.
In 2025, TikTok Shop will continue to implement the main strategies formulated in 2024, including strengthening infrastructure services, leveraging the advantages of content e-commerce to expand categories, and promoting the development of talent business. These strategies, especially infrastructure construction and category development, are long-term measures and may not be effective in the short term. Still, TTS believes that they will lay a solid foundation for the company's long-term development.
Last but not least, Reuters recently reported that TikTok might be sold in the US, and a separate app, codenamed M2, will be created for that market and released on September 5th. The current version of the app is said to be removed from app stores and would cease to function in March 2026. It remains to be seen if this will happen (and if the Chinese government will approve a sale of part of TikTok) and what the impact will be on TikTok usage and TikTok Shop if it does. [21]
Potential challenges coming with the launch of a new app are: [21]
Business migration and data transition. When merchants migrate their store data and product information to the new platform, data loss or errors may occur.
Policy and compliance changes. The new platform may face stricter US domestic regulatory policies. Merchants may need to provide more qualifications and compliance documents.
Traffic and user changes: potential loss of some users.
Supply chain adjustment. If the operating model or market positioning of the new platform changes, the merchant's supply chain may need to be adjusted accordingly. For example, if the new platform prefers to support local suppliers in the United States, overseas sellers may face increased competition and need to re-evaluate their supply chain strategy and consider whether to increase local procurement or cooperate with local suppliers.
Next week, we will take a closer look at TikTok Shop’s development in the Southeast Asian market.
Key Takeaways
The following key takeaways were created using Google Notebook.
• US Market Struggles & Lowered Targets: TikTok Shop's US sales are underperforming, with 2024 results at half the target and daily sales declining. The 2025 GMV target has been cut from $35 billion to $25 billion, with expected actual sales of $12 billion.
• Mixed European Performance: The UK market shows strong growth, becoming the fastest-growing e-commerce platform and third-largest online marketplace by 2024. However, other European markets like Germany, France, Italy, and Spain have seen lukewarm adoption and significantly lower daily sales.
• Latin American Expansion: Promising Mexico, Challenged Brazil: Mexico shows promising growth. Brazil, newly launched, faces high tariffs, weak logistics, and visa issues, hindering cross-border trade despite optimistic long-term forecasts.
• Shift to Content-Driven E-commerce: TikTok Shop is moving from a shelf model to a content-centric approach, prioritising live broadcast and video sales to achieve higher price premiums and average order values.
• Live Commerce Growth but Gaps Remain: Live e-commerce's GMV share is increasing in the US (20%) and UK, but remains well below China's Douyin (70%) and Southeast Asia (40%). Challenges include consumer preference for traditional retail, content production difficulties, and intense competition.
• US Team Instability & Cultural Clashes: The US e-commerce team faces frequent layoffs, high pressure, burnout, and significant cultural disconnects between Chinese leadership and US employees, leading to leadership reshuffles.
• Algorithm & Traffic Instability: TikTok Shop's 'goods find people' algorithm struggles with accuracy due to limited user purchase data, especially in the US, leading to inaccurate recommendations and wildly fluctuating traffic for merchants.
• Livestream Anchor Challenges: Cross-cultural live streaming is impacted by anchor backgrounds; Chinese anchors perform poorly in the US due to cultural and language barriers, while non-Chinese anchors have unstable streaming schedules. TikTok plans official live broadcast bases to cultivate local talent.
• High Subsidies Leading to Losses: TikTok Shop heavily relies on subsidies (product price reductions, logistics, traffic), with the US market showing a 25% subsidy rate, resulting in a 20% business loss rate. Users are price-sensitive and lack loyalty once subsidies are reduced.
• Future Uncertainties: Sales, New App, & Expansion: Future expansion includes new product categories and markets (e.g., Pakistan, Poland), with a focus on Brazil. However, the potential sale of TikTok in the US and the creation of a separate app ('M2') introduce major uncertainties regarding business migration, policy changes, and potential user loss.
Sources
This article has been compiled from an analysis of exclusive expert interviews within the Six Degrees Intelligence network, supplemented by insights from the articles listed below.
Images by Tech Buzz China’s Ed Sander, unless stated otherwise. These images may not be reproduced without Tech Buzz China's prior consent.
[1] Bloomberg 2025-02-17 [2] 36氪未来消费 2025-03-12 [3] Chinesellers 2025-02-11 [4] Chinesellers 2025-03-24 [5] 派代跨境2025-02-22 [6] Chinesellers 2025-06-10 [7] The Grocer 2025-02-20 [8] 派代跨境 2025-05-14 [9] Chinesellers 2025-07-08 [10] 派代跨境 2025-03-04 [11] 界面新闻 2025-02-19 [12] Chinasellers 2025-04-10 [13] Business Insider 2025-03-27 [14] Chinasellers 2025-04-14 [15] Business Insider 2025-04-23 [16] 出海商家 2025-05-26 [17] Technode 2025-06-17 [18] Chinesellers 2025-05-21 [19] Business Insider 2025-06-02 [20] Rest of World 2025-06-23 [21] 派代跨境 2025-07-07 [22] Marketplace Pulse 2025-03-06 [23] Momentum Works 2025-05-29