

Contents
Free section:
Paid section:
Things that caught our attention

Introduction
As all eyes were on the domestic food delivery market in 2025 and Meituan had to contend with JD's market entry and Alibaba’s integration of Ele.me and Taobao, we might forget its battles elsewhere in the world. In Hong Kong, the Middle East and Brazil, Meituan has been rolling out its international version of meal delivery and even grocery delivery.
In the first quarter of 2026, we will publish several Meituan-related reports on its international expansion and recent initiatives in the home market. Meituan’s global moves will be presented in two Tech Buzz China reports. In this first report, we examine how Meituan selected markets and launched its Keeta brand in Hong Kong and the Middle East. In the second report, which will follow at the end of this month, we take a closer look at its launch in Brazil, developments in profitability, and the outlook for Meituan’s globalisation.
These two reports are compiled from seven interviews with experts close to relevant companies in the period July to November 2025, as well as reports in the Chinese tech media over the past three years that chronologically lay out the development of Meituan’s overseas business.
In this first report, the section on Meituan’s selection of markets and the way it became the market leader in Hong Kong is free to read. The sections on its expansion into the Middle East, which are primarily sourced from expert interviews, are available only to paid subscribers. Become a paying subscriber to unlock the full report and support our in-depth research into key China tech trends.
We hope you enjoy this research and wish you a healthy and happy 2026!
Ed Sander, Tech Research Analyst

International expansion: Choosing markets
Looking back at Meituan’s internationalisation journey, it initially attempted global expansion in the online travel agency (OTA) sector, but failed in the Hong Kong market. This was mainly because in-store services require higher levels of localisation and are relatively difficult to implement. Based on this experience, Meituan ultimately chose the more suitable on-demand service model for internationalisation, particularly its asset-light food delivery platform.
Until 2023, Meituan’s overseas business had focused on investments instead of self-operated businesses. In 2018 and 2019, Meituan invested twice in Indonesian Gojek, the leading super app platform in Southeast Asia, which offers services including taxi hailing, delivery (food, parcels, groceries), online payments, and financial services. Previously, they also participated in the $100 million financing project of Indian food delivery platform Swiggy. In 2023, Meituan also entered into a deep partnership with the global online hotel booking website Agoda to serve Chinese tourists. [1]
Wang Xing, Meituan’s CEO, has said on many occasions that “the company will maintain a cautious attitude when it comes to overseas business expansion.” Still, he also believes that “globalisation is an absolute necessity and a huge opportunity.” [1]
And in 2023, the time seemed ripe, and Meituan launched its international brand Keeta, headed by Qiu Guangyu, who now reports directly to Wang Xing. The project leader has been promoted to Meituan’s top management team, underscoring Keeta’s key role within the group’s overall structure.
Meituan explained that Keeta is taken from the English word “cheetah, " an animal famous for their fast running speed. [2] Last month, it unveiled Kiki, its Keeta brand mascot, continuing the Chinese tradition of using cute animals to represent brands. At home, it already had a kangaroo for Meituan Waimai and an elephant for Xiaoxiang (Little Elephant) Supermarket.
Source: Keeta LinkedIn
From October 2022 to mid-2023, Zhu Wenqian, head of Meituan’s overseas strategic investment department, visited the Middle East several times to understand local business policies and the takeout industry's competitive landscape. In May 2023, Zhu Wenqian, along with Meituan CEO Wang Xing, Meituan Daojia Business Group President Wang Puzhong, and several other senior executives, returned to the Middle East and met with members of the Saudi royal family and ministers. Meituan tried to form a Middle East team and considered placing the first pilot city in Riyadh, but then this move was shelved because of “differences of opinion at the top. [1]
The Middle East and North Africa are also the best-performing regions for Delivery Hero's food delivery platform globally, ahead of Europe and the U.S., accounting for one-third of its revenue. Compared with China, the unit price of food delivery in the Middle East market is higher, generally above $30 (Meituan’s 2023 Q3 food delivery AOV was $7). [1]
Meituan had considered Dubai a priority pilot city for its entry into the Middle East. For many years, Dubai, the capital of the United Arab Emirates (UAE), has been the first choice for Chinese companies to expand into the Middle East due to its more comprehensive infrastructure, higher per capita GDP, and a more favourable business environment. UAE’s per capita GDP in 2022 was $54,000, while Saudi Arabia’s per capita GDP in 2022 was be $30,000. [1]
The food delivery market in the United Arab Emirates was expected to reach $2.79 billion by 2026, with 5.5 million users, representing nearly 50% penetration. However, the internal concern regarding the UAE was whether the volume and growth rate of food delivery orders in the Middle East market were worth doing, and whether it could be profitable in the short term. Especially considering that food delivery is a business that emphasises offline, strong performance and execution. In China, by comparison, Meituan’s 2022 food delivery GTV had approached RMB 940 billion (~$135 billion), and the number of transaction users had reached 678 million. [1]
While the plans for the Middle East were shelved, Keeta launched in Hong Kong, chosen as the first overseas market because of its similarity to the mainland’s culture and dining habits. [1] When planning its international expansion, Meituan evaluated several potential regions before ultimately choosing Hong Kong as its first target market. This decision was primarily driven by the operational advantages of Hong Kong’s unique geographic location and policy environment.
In 2024, after a successful launch in Hong Kong, Meituan planned to expand into mature markets over the next 5 to 10 years, including Saudi Arabia, Kuwait, Qatar, and Oman in the Middle East, and the UK and Germany in Europe. Meituan prefers to expand its business in economically prosperous regions, avoiding market promotion and education in less developed areas.
Meituan has consistently maintained a steady, cautious expansion strategy in overseas markets. To support business expansion, Meituan began focusing on Japan, South Korea, Southeast Asia, and the Middle East and conducted in-depth research. Before entering a new market, Meituan typically conducts market research two quarters in advance, using questionnaires and on-site visits, to ensure thorough preparation. Regarding localised data collection, Meituan acquires information on payment systems and third-party fulfilment data before entering a market. Analysing payment times, user matching, and delivery service capabilities ensures adequate preparation for market entry.
From a market-structure perspective, Southeast Asia lacks a single economy of sufficient scale; aside from Indonesia, the market sizes of other countries are relatively small. While the food delivery industry in Southeast Asia is expanding, the overall economic situation and market penetration remain low. Currently, the total transaction volume of food delivery platforms in Southeast Asia is approximately $17 billion, with an annual growth rate of only 5-6%. Although Vietnam and Malaysia are performing relatively well, the Southeast Asian market as a whole remains fragmented. Differences in local cultures and delivery costs complicate operations. This fragmented market structure poses a real challenge to food delivery platforms like Deliveroo.
Significant differences in market characteristics across Southeast Asian countries also pose challenges for implementing localisation strategies. Singapore and Hong Kong share many similarities, while Indonesia has a large ethnic Chinese population, and Vietnam is experiencing rapid growth but is challenging to manage. The region already has major competitors like Grab and Shopee Food, with Grab holding a market share of 5:3 or 1:1 in some countries. Given this situation, Meituan needs to optimise its localisation strategy first before gradually expanding its business. Due to limited resources, Meituan can initially operate only in a few major cities.
In 2023, Meituan was rumoured to acquire Foodpanda, a Southeast Asian food delivery brand, but ultimately decided not to proceed with the acquisition. Meituan found that Foodpanda’s Southeast Asian business was tricky to make a profit, the unit price per customer was too low, and the order growth rate was slow.” [1]
Meanwhile, the development potential of mature markets like Japan and South Korea is relatively limited. Japan, in particular, has a very mature convenience store system, and its food delivery business relies heavily on existing market share, with minimal room for further growth. Deliveroo’s actual market performance in South Korea and Southeast Asia has been suboptimal. However, it’s worth noting that Deliveroo achieved its profitability targets in the Middle East, indicating that its business model remains viable under certain market conditions.
The development trajectory of the European market is different. Since 2015-2016, the food delivery markets in European countries such as the UK and Germany have been established by platforms like Delivery Hero and Deliveroo, laying a solid foundation for the market. In 2024, Meituan intended to expand into the European market, but it has not yet launched.
The Middle East offers significant market potential given its large population. Saudi Arabia alone has 36 million people, while the entire Gulf region has a combined population exceeding 50 million. Meanwhile, Middle Eastern consumers demonstrate strong purchasing power; the average order value for food delivery services in the region is four to five times that of Southeast Asia. In contrast, Southeast Asian business models, with their limited profit margins, struggle to generate quick financial returns. The Middle Eastern food delivery market, however, is already worth tens of billions of dollars.
The Middle East also plays a crucial role in China’s Belt and Road Initiative, and businesses entering the Middle Eastern market can help enhance China’s international influence. Furthermore, the Middle East is widely recognised as having vast emerging-market potential, making it an even more attractive investment destination. Also, the Middle Eastern food delivery market is mainly dominated by local platforms, most of which have been acquired by overseas capital, resulting in relatively weak overall competitiveness.
Hong Kong, due to its developed nature, is considered an ideal testing ground. Similarly, Saudi Arabia and other Middle Eastern countries possess strong economies, mature markets, and significant growth potential. This strategy aligns with Meituan’s overall policy of selecting developed, mature markets with high growth potential. This approach could positively impact Meituan’s long-term prospects in the Middle East, as it allows the company to test and refine its business model on a relatively small scale before scaling up successful practices in a broader market.
Following a thorough analysis of market size, competitive landscape, and political stability, Saudi Arabia was chosen as the top overseas expansion target. Saudi Arabia is the preferred market primarily due to its large size and a relatively favourable competitive environment. Saudi Arabia’s food delivery market has an annual transaction volume of $10 billion and a 8% yearly growth rate. Furthermore, Saudi Arabia’s “Vision 2030” strategy provides policy support for businesses, including investment incentives and tax breaks, which are highly beneficial for business development. Notably, Saudi Arabia’s digital transformation goals align closely with Meituan’s business operation model. Meituan would leverage its strengths in delivery and marketing to gradually expand its business in new markets.
Although Saudi Arabia is the largest single market, intense competition and a long market-penetration period have led companies to be more optimistic about expanding their businesses beyond Saudi Arabia. Uber Eats exited the Saudi and Egyptian markets in 2020, after taking a hard look at its “business metrics of delivery services in the competitive market”. [3] However, the economies of scale in the Saudi market can improve operational efficiency, and increased order density will lead to efficiency optimisation. Successful operational experience accumulated in the Saudi market will support rapid expansion in other markets.
The success achieved in the Saudi market provided valuable insights for the company’s expansion into other parts of the Gulf region. Between August and October 2025, Keeta expanded to Doha, Qatar (August 19th), Kuwait (September 15th) and two cities in the UAE, Dubai (September 27th) and Abu Dhabi (October 28th). It officially launched in Brazil on October 30th, beginning with pilot operations in Santos and São Vicente (more on this in part 2 of this report). [4] In March 2025, a Keeta employee told Rest of World that Egypt was another location under consideration for further expansion, but it has not yet launched. [3]
Keeta launches in Qatar. Source: Keeta LinkedIn
The perception of Latin America as a crucial strategic node, coupled with the trend of Chinese companies expanding their global business influence, also prompted Meituan to make this internationalisation decision. While Latin America is also an essential part of the Belt and Road Initiative, current strategic planning leans towards the Middle East due to its more compatible policy environment and development prospects.
According to Meituan’s calculations, Brazil ranks fourth in the global food delivery market, with a 20% growth rate and a merchant commission rate of up to 27%. In the long run, this market has considerable profit potential. Brazil’s overall market size is larger than that of the Middle East, accounting for 8% of the global food delivery market, while the Middle East accounts for only 5%, ranking fifth globally. Nevertheless, the Middle East market is expanding faster and is expected to achieve profitability sooner than Brazil.
Meituan’s strategy is to capture market share through meticulous management and subsidy policies, and to solidify its position through algorithms. As a testing ground for Meituan’s international expansion, Keeta currently focuses primarily on the Middle East and Latin America, and may expand to Southeast Asia and other regions in the future.
The Conquest of Hong Kong
While meal delivery gained popularity in Hong Kong during COVID, it accounted for only 8.3% of the catering market, far behind the 21.9% share in mainland China. In 2020, due to the pandemic, it reached 2 million, but it remained flat year-on-year in 2021. The user penetration rate of food delivery platforms in Hong Kong was only 20% in 2017. From 2019 to 2021, due to the pandemic, it increased but remained below 30%, compared with more than 50% in mainland China. In 2022, the penetration rate declined year over year. [2]
Hong Kong’s small city size, high labour costs, citizens’ habit of eating out, and the convenience of dining out all constrain the growth of the food delivery industry. In addition, high prices, unreliable delivery, and limited supply options were pain points that the two existing food delivery platforms in Hong Kong, Foodpanda and Deliveroo, had not addressed effectively. [2]
Among the three food delivery platforms in Hong Kong, Foodpanda, Deliveroo and Uber Eats, Foodpanda had the largest market share of 51%, with about 1,273,300 active users, much higher than the other two platforms, and its services cover more than 7,000 restaurants. [2] Deliveroo, one of the three major food delivery platforms in Hong Kong, offered a diversified range of services, including food delivery and delivery from retail partners such as 7-Eleven. Foodpanda attracted customers with premium services, membership programs, and free delivery.
Deliveroo and Foodpanda had previously aggressively subsidised takeout orders, but after the subsidies ended, most people returned to dining at physical restaurants. With high labour costs and a dense restaurant scene in Hong Kong, especially in urban areas where restaurants are just downstairs, dining in or self-pickup costs were lower for consumers. [5]
Despite these challenges, Meituan’s food delivery business began planning its entry into the Hong Kong market in October 2022. It started recruiting for staff positions in strategy, business analysis, and user operations, with Hong Kong as the work location, and “international experience preferred” and “Cantonese and Chinese” as recruitment requirements. [2]
In February 2023, it was reported that Meituan would enter Hong Kong, and recruitment advertisements were placed for delivery riders, business channel managers and other positions. In April, some netizens discovered that Meituan was testing food delivery services in Hong Kong. On May 22nd, 2023, Keeta officially launched in Hong Kong. The Keeta Rider app had already been made available before that, and the first courier rider introduction meeting was held on April 4. [2]
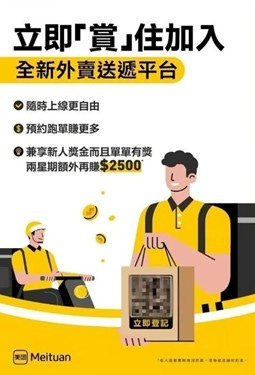
Join now on the brand new food delivery platform, Meituan! Go online anytime for greater freedom, schedule orders and earn more, plus newcomer bonuses and extra rewards on every order – earn an additional $2500 for two weeks! Register now! (Source: Linkshop)
Keeta set up a customer service team based in the Greater Bay Area, rather than in Causeway Bay, where housing prices are high. [6]
Keeta captured 20% of the market share in the region within a month of landing in Hong Kong (the local food delivery platforms Foodpanda and Deliveroo had 64% and 36%, respectively). [1] In July 2023, Deliveroo replaced its head of Hong Kong, and Foodpanda followed suit in August with a promotional “Three Meals for $14” campaign. [7]
Keeta adopted a strategy of expanding new districts in Hong Kong month by month. The densely populated Mong Kok and Tai Kok Tsui areas were the first stops, and the program gradually expanded to new districts, aiming to complete coverage of Hong Kong by 2023. [2] Meituan primarily targeted young people and actively promoted its services to attract new users.
In July 2023, Keeta launched a voting feature in the app to prioritise expansion areas based on user votes. [5] As of September 2023, Keeta covered the entire Kowloon area and expanded to the other side of Hong Kong Island, opening services in Central and Western District, Wan Chai District and Eastern District. [1]
Meituan had not allocated many resources to Keeta (possibly because it was competing with Douyin in the domestic local services market and with Pinduoduo in community group buying) and had not set high expectations for it. Due to high delivery fees, slow delivery speeds, and the rise of offline catering, Hong Kong users were not very willing to use takeaway services. [1] Keeta covered nearly 50% of the population in the delivery area, excluding the southern district of Hong Kong Island and the entire New Territories. [5]
In September 2023, Keeta also launched a “Free Shipping for All” campaign, under which each user could enjoy free shipping on one order per day, with a maximum discount of HK$45 (~$5.75). This promotion was more generous and broader than the “Free Shipping on Thursdays, Fridays, and Saturdays” introduced by Keeta in July and the “Daily Half-Price Deals” launched in the app in August. [5]
In terms of discounts, Keeta launched a “billion reward” plan that included user coupons and special discounted meals co-launched with restaurants. For example, with coupons, Hong Kong citizens could eat a McDonald’s Big Mac set meal for less than HK$50 (~$6.50) with shipping. [2]
On September 20 2023, Keeta and Tan Zai San Ge Rice Noodles jointly launched a single-person meal. The single meal costs HK$29 (~$3.75) and includes no delivery fee. The original price of a single meal was HK$49.9 Hong Kong dollars, while the delivery fee would typically be $HK20-30. On the day the promotion launched, Keeta ranked first in the Hong Kong App Store's free app list. [6]
Keeta aimed to increase the average order value to HK$60-70 (~$8-9). Simultaneously, it focused on leveraging its fast delivery advantage to improve user satisfaction. Given price competition in the Hong Kong market, Meituan offered targeted subsidies on select products. Its services are primarily for Hong Kong office workers and students, offering daily dining options. While restaurant meals in Hong Kong typically cost HK$80- HK$100 (~$10-$13), Meituan offered more affordable options. Its strategy was to attract users by providing frequent, low-priced services, thereby increasing order volume and enhancing user loyalty.
By November 2023, Keeta had become the second-largest food delivery platform in Hong Kong, accounting for 30.6% of total delivery orders in the region, only behind Foodpanda and ahead of Deliveroo by nearly 3%, according to statistics from third-party platform Measurable AI. Keeta claimed to have around 10,000 merchants and reports an average monthly merchant growth rate exceeding 30%. [8]
In early 2024, Keeta launched a takeaway self-pickup service, following the examples of Deliveroo and Foodpanda. Consumers could choose driver delivery or in-store pickup when placing an order, but Keeta had partnered with select merchants to offer higher discounts for self-pickup takeaway orders. More than 1,000 restaurants offered discounts of up to 20% with no minimum spend. [9]
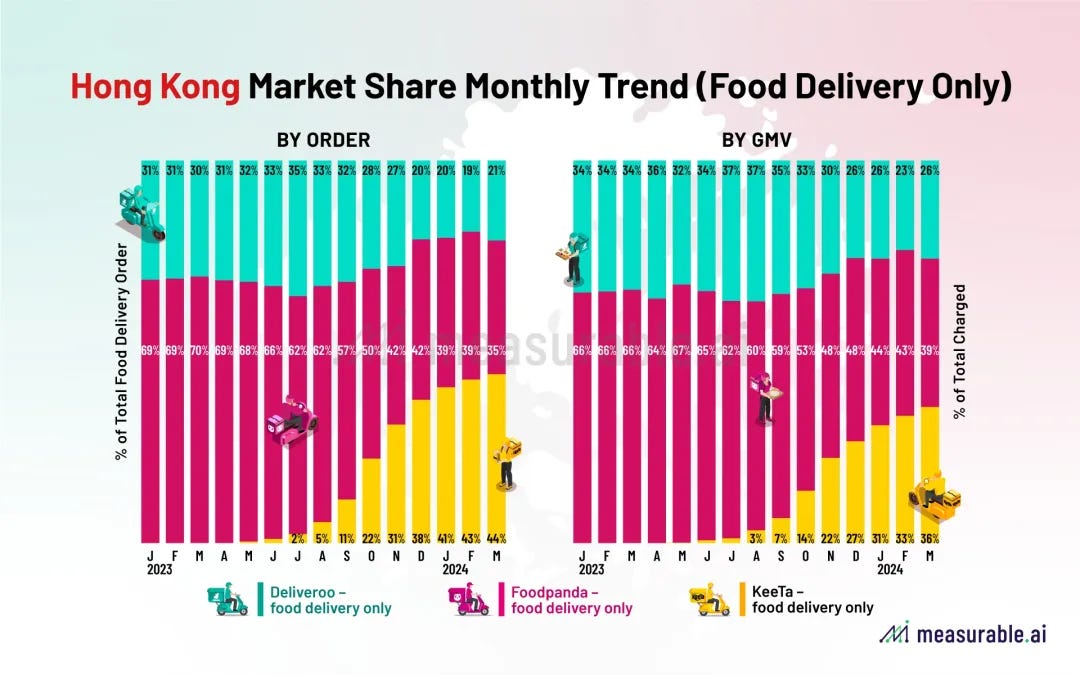
Source: Measurable AI [7]
According to Measurable AI, by March 2024, Keeta's order share had jumped to 44%, making it the takeout platform with the largest order volume in the Hong Kong market, surpassing Foodpanda (35%) and Deliveroo (21%). However, Keeta was not yet the first by GMV. [6]
In addition to free delivery, Keeta’s key strategy to become the number one app in Hong Kong by order volume was to optimise its product range. In the past, the average customer spend on Hong Kong’s major food delivery platforms, Foodpanda and Deliveroo, was typically between HK$100 and HK$200 (~$13 - $26), and orders were mainly for multiple people rather than single consumption. Keeta added a single-person meal and engaged with international brands such as McDonald’s to enable them to offer a discounted all-inclusive package at HK$30-60 (~$4 - $8). The takeaway price is the same as, or even lower than, dine-in, to expand scale and user base. [10]
About 30% to 40% of Keeta’s orders in Hong Kong were discounted single meals. Some Hong Kong users used to order takeout only 2-3 times a month, but the lower takeout prices increased their frequency. But during the promotion, they ordered 5-10 times per month, and some people who didn’t order takeout also started placing orders. [10] Half of the single-meal users placed repeat orders. The most popular restaurant is McDonald’s, although specific order quantities were not disclosed. [5]
As of May 22, 2024, more than 2 million users had downloaded the app, indicating that nearly 30% of Hong Kong residents were already Keeta users. By mid-2024, more than 10,000 restaurants had opened, offering a variety of cuisines, including Chinese, Western, Japanese, Korean, and Thai. [6]
To address the delivery problem, Meituan initially advertised a maximum rider income of HK$35,000 (about $ 4,500), paid riders higher compensation per order, and lowered the rider threshold, allowing “infantry riders” with a Hong Kong identity to join and deliver food on foot. [1] Still, in May 2025, Keeta deliverymen in many districts of Hong Kong were dissatisfied with the platform’s reduction of unit prices and the implementation of priority dispatch and order-grabbing mechanisms. [11]
When it launched, Keeta implemented an on-time guarantee service. By mid-2024, the on-time guarantee rate was stable at over 98%, and the average delivery time was under 30 minutes. Some riders reported that, compared with the early stage of operations, delivery times had shortened significantly, while other food delivery platforms have increased their order remuneration. [6] In a test of food delivery platforms conducted by the Hong Kong Consumer Council, Keeta ranked highest in delivery performance, with its deliveries significantly more punctual than competitors’. [9]
One of Keeta’s advantages compared to its international counterparts was its more efficient delivery algorithm. According to calculations by Fangzheng Securities, as the number of users and orders increases, the average delivery cost could be reduced to HK$17 (~$2.20), down from around HK$30 (~$3.80) in 2023. In 2023, it was rumoured that Keeta had recruited hundreds of riders from Shenzhen to deliver meals in Hong Kong, possibly to proactively reduce delivery costs and improve speed. However, sources close to Meituan claimed this was unlikely due to policy restrictions. [5]
In mid-2024, Keeta attracted convenience stores such as 7-Eleven to join its delivery platform, as the firm sought to add more merchants and categories as part of its expansion efforts. 7-Eleven, which joined Keeta on 19 July, offered a range of hot food, snacks, and beverages while excluding non-food items for Keeta delivery. [12]
By August 2024, all three platforms were running new promotions weekly at a similar intensity. Deliveroo and Foodpanda, in particular, offered self-pickup for takeout orders, with no queuing or delivery fees. With coupons, prices can be as low as 60% off dine-in prices. [5]
One and a half years after entering the Hong Kong market, Keeta had doubled local takeaway orders from 150,000 to an average of more than 300,000 per day in early 2025. [10]
In April 2025, Deliveroo announced its withdrawal from Hong Kong after 9 years of operations. After Keeta had entered the market, Deliveroo’s order market share had continued to decline. Keeta targeted the demand for single meals, penetrated office areas, and heavily subsidised, and it took only one year to become the number one in the local order share. [13]
In Hong Kong, Keeta launched attacks on other platforms by relying on the “growth first, profit later” strategy. It required significant investments: higher salaries for deliverymen, lower commission rates for merchants signing contracts with Keeta, and higher subsidies and lower prices for users. [11] Still, at the earnings call in October 2025, Wang Xing announced that Keeta’s Hong Kong business had achieved profitability. Since May 2023, this milestone has taken 29 months, six months earlier than the initial expectation of “profitability within three years”. [14]
Hong Kong’s strategic goals for 2025 and 2026 are to maintain stable profitability while serving as an incubation platform for new business models and to accumulate operational experience for global expansion. The main businesses in Hong Kong include food delivery and self-pickup services. Plans are to increase resource investment in instant retail in 2026 and explore innovative models, such as in-store consumption services. Furthermore, the Hong Kong market will explore new avenues in international payment solutions and user profiling, while also testing various business models, including Keemart (see below), supermarkets, power banks, and hotels. Given the relatively small size of the Hong Kong market, companies are adopting a cautious operating strategy to validate the feasibility of the three-year development plan.
Still, Meituan considered Hong Kong ‘just’ a test to understand the entire chain, to go further overseas... [6]
Heating up the Middle East
Source: Keeta LinkedIn
The overall size of the food delivery market across the six Gulf states was about $25 billion in 2024, and was expected to reach $30 billion by 2025. The Saudi market accounts for about 40% of the food delivery market in the six Gulf states.
Meituan has outlined a three-year plan to expand Keeta across all six Gulf Cooperation Council (GCC) countries: Saudi Arabia, the UAE, Qatar, Kuwait, Oman, and Bahrain. [15]
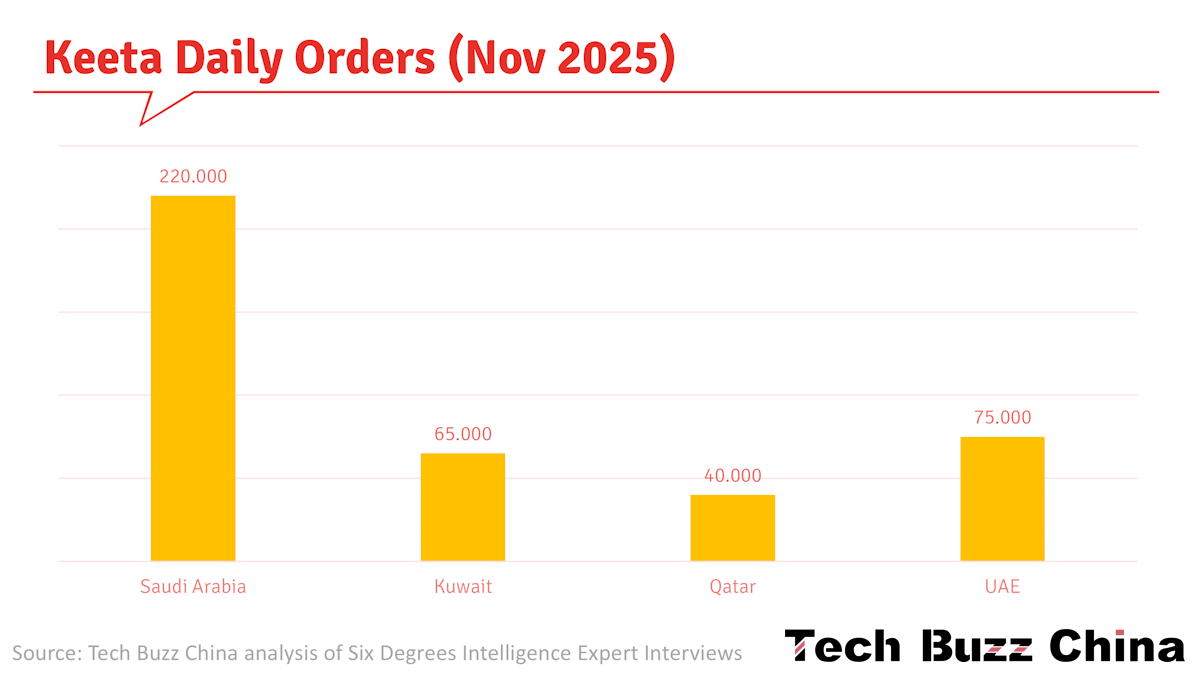
Keeta currently operates in four of these countries: Saudi Arabia, the UAE, Kuwait, and Qatar. These markets account for over 80% of the potential market across the six Gulf Cooperation Council (GCC) countries. The two remaining smaller countries (Bahrain and Oman) are expected to complete their launch before the Spring Festival. Recent order growth and city expansion in the Middle East have far exceeded expectations, which, while leading to higher losses, may also accelerate the time to break even or cost recovery.
In early 2025, Keeta’s daily order volume in the Middle East reached 400,000, with average order value slightly below current levels. Since August 2025, order volume has increased due to optimisation and adjustments in some regions and the expansion into new cities, but monthly losses have also widened. By November 2025, Meituan processed approximately 700,000 orders daily in the Middle East, with its main business concentrated in Saudi Arabia and surrounding countries. In contrast, its operations in other markets, such as Brazil, are still in their early stages and on a smaller scale.
In November 2025, the monthly gross merchandise volume (GMV) in the Middle East was approximately RMB 2.7 billion (~$400 million). However, this figure includes initial orders from newly launched cities in August and September, including Dubai, Abu Dhabi, Kuwait, and Qatar, totalling nearly 200,000. Therefore, it isn’t easy to directly extrapolate full-year performance from annual proportions.
· Saudi Arabia, in particular, as a key market in the Middle East, has performed exceptionally well in increasing market share and reducing losses. Rider efficiency has improved, and the testing of user delivery fees has not negatively impacted order volume. Saudi Arabia’s market share by November had increased to 28%, approaching the leader HungerStation’s 33%.
In the UAE, the company’s operations are primarily concentrated in Dubai and Abu Dhabi, with a daily order volume of 70,000-80,000, representing approximately 10%-20% market share.
The Kuwaiti market has been operating for two to three months, with a daily order volume of around 60,000 to 70,000. The total daily order volume in the local market is approaching 500,000, giving the company a slightly higher market share.
The Qatari market sees approximately 40,000 orders daily, accounting for 12%-13% of the local market, with total daily order volume across the entire market between 300,000 and 400,000.
Although initial market share in the UAE, Kuwait, and Qatar is relatively low, these markets are considered to have significant growth potential and the possibility of rapid development.
In the Middle East, Meituan will primarily invest in the further development of existing operating areas, with a focus on key markets such as Saudi Arabia, the UAE, Qatar, and Kuwait. Saudi Arabia is considered the preferred market for investment, with companies planning to optimise costs through business expansion, ultimately aiming to stop losses and achieve market leadership. Meituan’s goal is to become the market share leader in Saudi Arabia by 2026 and further reduce losses.
Meanwhile, the GCC region plans to further reduce losses and expand its market share by 2026. However, after Saudi Arabia, the expansion is accompanied by greater uncertainty because there are more prominent leading players in markets outside Saudi Arabia: in the United Arab Emirates, Kuwait, Qatar, and other countries, Talabat’s market share is above 50%, and in some cases above 70%. [13]
In the UAE, Keeta faces a highly competitive market with three leading food delivery companies: Talabat (in 2015 acquired by Germany’s Delivery Hero), Careem, and Deliveroo, requiring companies to subsidise prices to maintain and expand market share continuously. Similarly, continued subsidies will be employed to maintain growth momentum in Qatar and Kuwait.
Saudi Arabia
In terms of market size, Saudi Arabia’s food delivery market was valued at approximately $10 billion in 2024, with a projected growth rate of 15%-18%. The entry of new platforms could boost the growth rate to 22%-25%. In an interview with local media, Qiu Guangyu, head of Keeta, predicted that the Saudi food delivery market would grow by at least 20% year over year in 2025. [10]
Saudi Arabia has a population of 35 million, 60%-70% of which are locals, and is relatively wealthy. Most people order food as a family unit. The starting price is 100 Saudi riyals (~$27), and the minimum delivery fee for an order is as high as 15 Saudi riyals (~$4). The user penetration rate of the food delivery market was 44.2% in 2024. In contrast, China, as the world’s largest food delivery market, had an estimated user penetration rate of 54.5%. [6]
KeeTa initially expressed its intention to acquire a leading food delivery platform in Saudi Arabia, and the other party enthusiastically introduced the company’s business and local market conditions. After receiving an offer of 1 billion, KeeTa stopped contacting. [6]
Meituan’s expansion strategy in Saudi Arabia mirrors its approach in Hong Kong: piloting in smaller cities before a large-scale market rollout. In Saudi Arabia, Meituan selected Al Kharj, near Riyadh, as its pilot city and launched there on September 9, 2024. A month later, Keeta launched in the capital Riyadh. Wang Xing, who personally oversees the overseas business, visited the Riyadh office and delivered an English-language speech to encourage the team. Qiu Guangyu, who is directly responsible for Keeta, has also relocated from Hong Kong to Riyadh. [7] Upon entering Saudi Arabia, Keeta publicly stated that it would invest US$266 million (approximately 1 billion riyals) to support the growth of its business in the country. [7]
In 2024, Tech Planet listed several challenges Keeta would face in Saudi Arabia: [6]
Promotion capability could not be fully utilised in Saudi Arabia in the short term, as local expansion requires a large number of Arabic-speaking talent.
Local life companies need to retrain their teams in each country, and there is almost no global network effect. The team in Hong Kong cannot be transferred to Riyadh, and the Riyadh experience cannot be replicated in New York.
Saudi Arabia’s online payment system is not yet mature, and many orders are paid on delivery, which significantly reduces delivery efficiency.
During Ramadan, Muslims abstain from eating or drinking from sunrise to sunset, which significantly reduces transportation capacity. In Saudi Arabia, a food delivery platform went bankrupt due to a severe reduction in transportation capacity during Ramadan, which led to a significant decline in orders afterwards.
Most of the Saudi deliverymen are Pakistanis and Indians, and Saudi Arabia requires work visas that companies have to handle by themselves, which is costly and complicated.
When building your own delivery team, you also have to consider the required ratio of Saudi locals. (see ‘Couriers’)
Improving delivery efficiency in Saudi Arabia through algorithms is not feasible in the short term. Compared with e-commerce platforms, local life requires higher granularity in fulfilment. For example, the map of Meituan Takeout must be accurate at the level of individual buildings to estimate delivery times. The local postal address system and the map accuracy are not perfect. Even for e-commerce items, secondary and tertiary delivery is standard, and Google’s GPS navigation may be more reliable. This means that if Meituan wanted to improve delivery efficiency, it would first need to complete the infrastructure.
Due to high temperatures and raging sandstorms, most deliverymen in Riyadh prefer to deliver food by motorcycle or car. Ultra-high temperatures of 30 to 47 degrees Celsius, intense ultraviolet rays, and dry air all test physical fitness and willpower. If the policy allows, Meituan’s use of drones to deliver food may significantly improve efficiency.
Furthermore, strict local labour policies and religious taboos could further complicate business. [7]
Despite all these challenges, Keeta did very well. In early 2025, it ranked number one in free app downloads on Apple’s App Store in Saudi Arabia, with 3.6 million downloads from October to January, according to market intelligence firm Sensor Tower. [3]
By March 2025, Keeta operated in 9 cities across Saudi Arabia, covering nearly all cities with populations of more than 1 million and reaching almost half of the country’s population. An employee of Keeta in Riyadh told the media, “According to the company’s internal assessment, Keeta has firmly ranked third in the market, and the goal is to become the first in the market as soon as possible.” [11] Within a year, Keeta had expanded to 20 cities. [16]
Qiu Guangyu noted that the Saudi market's challenge is high delivery fees, which deter many people from ordering takeout. Centralised order delivery, lower unit prices, and improved efficiency were Meituan’s aims in Saudi Arabia, as in China. [10]
Meituan’s research found that local food delivery platforms charge users 15-20 Saudi riyals (~$4 - $5.33) in delivery fees per order, but typically subcontract the service to providers at around 10 Saudi riyals (~$2.70). Riders receive less money, and the platform can earn an additional 5-10 Saudi riyals. Keeta expected to reduce food delivery fees through collective delivery, the order scale effect, and the compression of intermediate links. [10]
As it had done in Hong Kong, Keeta offered compensation for late deliveries and substantial discounts. To attract new customers, Keeta offered 100 Saudi riyals ($26.65) in sign-up vouchers, 50% off first orders, and waived delivery fees. [3] The 50% discount on the first order and free delivery were so attractive that they directly caused the transportation capacity to collapse. [7]
A user in Riyadh said, “Before Keeta came, local food delivery fees were high and delivery time was long, but now it has improved.” Soon, HungerStation and Jahez also started offering discounts and promotional subsidies. [13] Rest of World wrote: “Its aggressive, price-slashing strategy is squeezing smaller players and challenging dominant platforms in the lucrative Middle Eastern market, which could be a springboard for other international markets.” [3]
The platform and merchants share Keeta’s subsidies in Saudi Arabia. While HungerStation has a fixed commission rate of about 15%, Keeta required merchants to share some activity-related expenses in addition to the commission, which put more pressure on them. [7]
As Saudi business expanded, Keeta’s new office area was being renovated in mid-2025. Located opposite the Five Savings mall in Riyadh, which has exceptionally high local customer traffic, Meituan has leased two floors totalling more than 4,000 square meters. [17]
Source: Keeta-Global.com
Couriers
In Saudi Arabia, the local government, to protect local employment, requires companies to hire 20%-50% of their workforce as Saudis, depending on the industry. However, locals do not favour delivery, takeout, and other physical labour, and only a 10% ratio is required. Meituan can recruit takeout drivers at a lower cost. [10] Keeta’s basic requirements for riders strictly follow local employment policies, including a continuously validly registered car or motorcycle, a work permit in the Kingdom of Saudi Arabia, a valid driver’s license, etc. [7]
By early 2025, Meituan had not yet established its own rider team similar to the domestic delivery team. Instead, it cooperates with local service providers to recruit riders. The basic monthly salary for motorcycle riders is 2,000 Saudi riyals (~$530), and for drivers with their own cars is about 5,500-6,000 Saudi riyals (~$ 1,450 - $ 1,600), plus additional performance bonuses. Considering the rental and fuel costs of car drivers, their income is not much different from that of Meituan’s domestic food delivery riders. In contrast, riders' highest income is about one-third of Hong Kong's. [10]
Regarding workload, riders are required to be online for 10 hours per day, but there is no specific daily order volume requirement in the early stage. In 2025, as order volume increased, riders in some cities received notices from service providers that they must deliver 200-300 orders per month, temporarily below the 400-450 orders per month required by platform cooperation service providers working for Hunger Station and Jahez. [10]
To ensure on-time delivery, Keeta chose to deploy more riders in specific areas. Riders may take 4 days off per month, but they may not take holidays during the peak order period from Thursday to Saturday. Users in Riyadh and Jeddah experienced delayed deliveries when placing orders in the early days of the city's opening, prompting customer compensation. With the increase in riders, most orders can be delivered within the estimated time provided by the Keeta system. [10]
Competition
Keeta faced major competitors in Saudi Arabia:
Talabat, the earliest food delivery company in the Middle East, was established in 2004 and acquired by German Delivery Hero in 2015.
Hunger Station, a Saudi platform, was also acquired by Deliver Hero in 2016.
Jahez is a local food delivery platform established in 2016.
In addition, competitors include more than a dozen delivery service platforms, such as the aggregation platform Wssel. [6]
From a business model perspective, HungerStation’s operational strategy primarily targets family gatherings or friend get-togethers with an average order value of $20 or more. It generates profit from higher average order values, platform commissions, and delivery fees, but order volume is relatively low. In contrast, Jahez focuses on local chain restaurants and small and medium-sized businesses, such as local burger chains and hand-pulled pancake shops. At the same time, HungerStation tends to partner with nationally renowned brands like McDonald’s and Starbucks.
Regarding merchant resources, a clear differentiation is evident. HungerStation partners with approximately 25,000 stores, mainly national chain restaurants; Jahez covers about 22,000 stores, primarily serving local brands; while Meituan, through its comprehensive coverage strategy, has integrated with approximately 30,000 stores, encompassing both national chains and small and medium-sized merchants. It is particularly noteworthy that Meituan has adopted a refined China-specific operational model for its business development team and on-the-ground promotion, resulting in operational efficiency surpassing its competitors’. Its business development team not only serves large chain clients but also focuses on developing small and medium-sized merchants, creating new consumption scenarios such as single-person meals and single-person dining, and attracting blue-collar workers and single-person consumers.
In terms of delivery speed, Meituan demonstrates a clear technological advantage, with an average delivery time of 33 minutes, significantly better than HungerStation’s 42 minutes and Jahez’s 45 minutes. Despite Middle Eastern regulations requiring platforms to recruit riders through third-party labour agencies, Meituan has excelled in rider dispatching and on-time delivery management, thanks to its advanced algorithmic technology, which has laid a solid technological foundation for its improved market position.
Before 2024, Saudi Arabia’s food delivery market was dominated by HungerStation, which held over 40% of the market share, and Jahez, which had over 30%, together controlling nearly 80% of the market. Before Meituan entered the Saudi market, local food delivery platforms were generally profitable, with a profit of about $ 0.30- $ 0.45 per order, maintaining a profit margin of around 2%.
By March 2025, Keeta held 10% order share in Saudi Arabia, according to a recent report from Bengaluru-based business consulting firm Redseer. Its market share as of January had surpassed that of more than 10 smaller delivery apps. Keeta’s vouchers, free delivery, and discounted meals mainly impacted these smaller players and the leading players not so much … yet. [3]
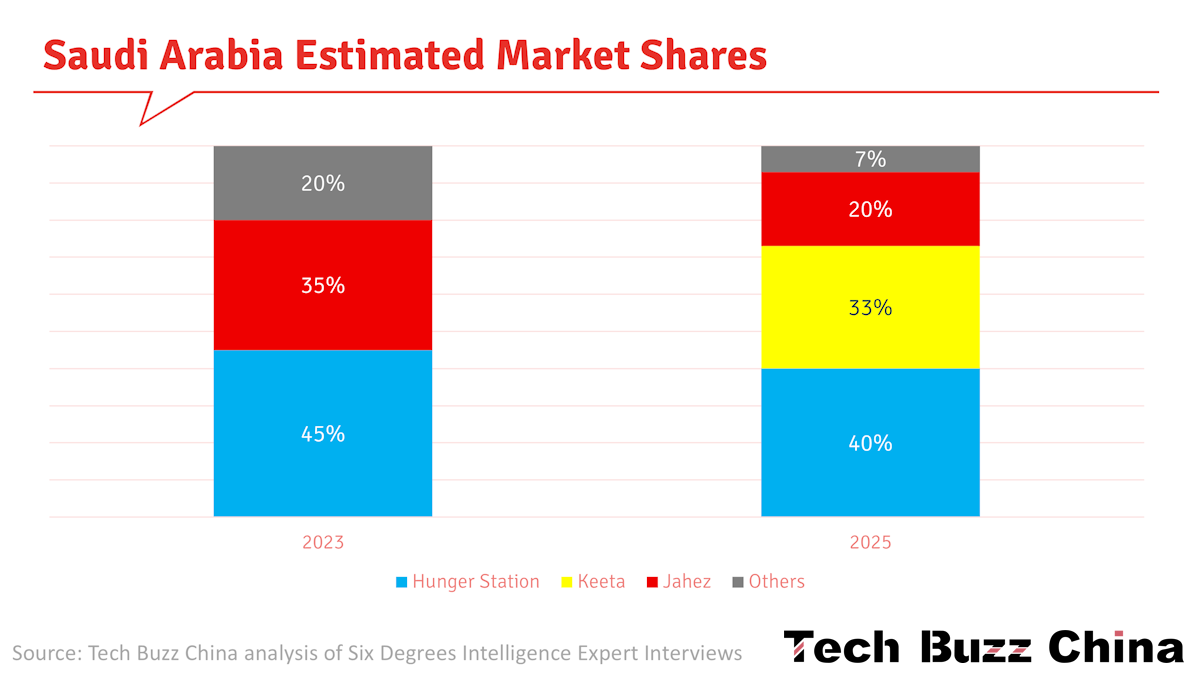
By November 2025, the Saudi food delivery market exhibited a “432” distribution pattern: HungerStation ranked first with a 40% market share, followed by Meituan at 33%, and Jahez in third place at over 20%. By transaction volume, HungerStation remains the top spot, while Meituan and Jahez each account for 27%-28%, creating a competitive landscape with a tie for second or third place.
Building an Ecosystem and Keemart in the Middle East
According to multiple third-party data sources, the growth rate of grocery delivery in Saudi Arabia has consistently outpaced that of food delivery. A report by Lucidity Insights shows that by 2028, the size of the Saudi grocery delivery market is expected to grow to $2.8 billion at a compound annual growth rate of 18.2%, which is three times the growth rate of the food delivery market. According to data from the Saudi General Statistics Bureau (GASTAT), 63% of the Saudi population is under 30. Whether it is the desert's high temperatures or the younger population, both are more receptive to instant delivery services across more categories. [17]
The fresh grocery retail (instant retail) market is about 16% the size of the food delivery market. By 2024, Saudi Arabia’s fresh grocery retail market reached $1.6 billion, while the overall market size in the six Gulf states was approximately $3.4 billion, projected to grow to $4 billion by 2025.
As such, it’s no surprise that Meituan was interested in this market …
Meituan Xiaoxiang (Little Elephant), Meituan’s front-end warehouse grocery delivery business, has two main development strategies: expanding product categories and expanding its geographic coverage. In terms of geographic expansion, Xiaoxiang Supermarket is currently focused on its presence in first- and second-tier cities in China and is actively expanding into international markets.
In December 2024, three months after Meituan launched Keeta in Saudi Arabia, it was reported that Meituan Xiaoxiang had started overseas expansion, with Saudi Arabia as its first stop, led by “old Meituan employee” Liu Wei. Members of the overseas project team were primarily drawn from Meituan Youxuan (Meituan’s community group-buying platform, which recently shut down), Kuailv (its B2B delivery service), and domestic Xiaoxiang businesses. At the time, the Xiaoxiang overseas expansion team already had 100+ products and tech people, as well as dozens of business executives. [18]
By May 2025, Keemart had begun recruiting staff, including an investment procurement manager, an operations manager, and a BDM (business development manager). At the same time, its delivery application, Keemart Courier, launched on the App Store, supporting registration via email and Saudi mobile phone numbers. [17]
On May 22nd 2025, Meitan launched its front-end warehouse grocery delivery business in the AI Yasmin and Granada areas of Riyadh. The initiative was launched under the name Keemart to create a clear link with Keeta. It would gradually provide complete coverage of the other regions in Riyadh by 2025. [17] Keemart is available in the Keeta App, a strategy similar to its reliance on the Meituan platform in the domestic market, covering categories such as fruits and vegetables, snacks, beverages, dairy products, pantry necessities, personal care products and cleaning supplies. [11]
In July 2024, Keeta’s supply categories in Hong Kong expanded beyond food delivery to include convenience stores, and 7-Eleven stores also opened at that time. [18] However, unlike with Keeta, Meituan had not used Hong Kong as a test market for Keemart. Hong Kong has a high density of convenience stores, and users’ reliance on online grocery orders is not high. The profit margin would be insufficient, and it could end up burning cash. As such, Saudi Arabia was the first overseas market for this business model. Keemart would help further enhance the richness of Meituan’s overseas products and increase transaction frequency. [17]
Meituan was not the only company considering grocery delivery in Saudi Arabia. According to a report by LatePost, the management of Dingdong Maicai, one of Meituan’s competitors in the Chinese front-end warehouse market, decided, after research, to enter Saudi Arabia in the third quarter of 2024. It planned to open its first front-end warehouse before March 2025. However, in early February, when it learned that Meituan’s Xiaoxiang Supermarket was considering entering Saudi Arabia, Dingdong CEO Liang Changlin announced at an internal meeting that he would temporarily abandon plans for the Saudi market, avoid losses, and focus on domestic business. [17]
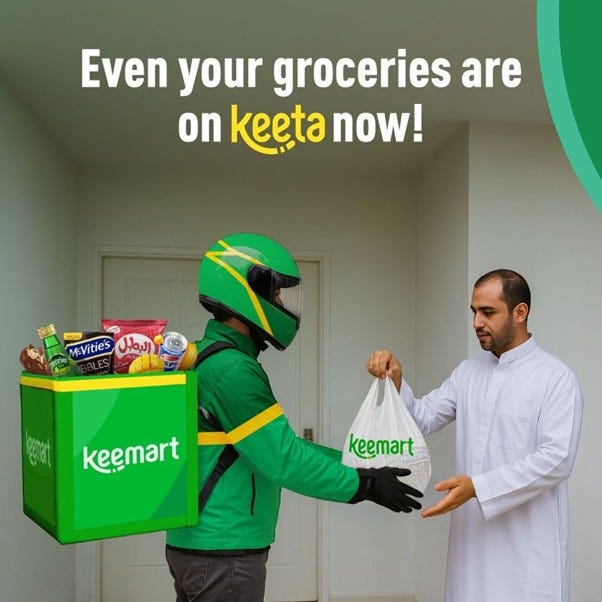
In the early stage, Keemart continued to use large-scale subsidies to gain market share and launched a first-order discount of 1 Saudi riyal (~$0.27) on mangoes, bananas, eggs, and other products. It also offered weekly discounts of 15% to 20% on select products, as well as promotions such as “buy one get one free” and free delivery. [17]
Source: Keeta LinkedIn
Meituan has several advantages with Keemart in Saudi Arabia: [18]
Policies in the Middle East are favourable, and overall development is slower than in developed countries, creating more opportunities.
Given Keeta’s food delivery foundation, challenges of customer acquisition costs and user stickiness are easier to solve than those of competitors. (see below)
After Xiaoxiang’s model is implemented, many of Meituan’s self-operated products and supply chains can be expanded overseas, creating new opportunities.
Meituan plans to build a unique competitive advantage by introducing a new business ecosystem, rather than relying solely on traditional food delivery services. Keemart offers fresh food, daily necessities, power banks, and other services to create synergistic ecosystem effects and avoid falling into price competition.
Competitors have begun to emulate Meituan’s ecosystem strategy, for instance, by integrating instant retail and self-pickup services into their platforms. However, due to a lack of core capabilities in independent product selection and supply chain operation, they have encountered difficulties at the business DNA level. Successfully operating a fresh food retail business requires advanced algorithmic technology, strong data integration, and efficient supply chain management, areas where competitors currently face significant technological barriers. While they may compensate for these shortcomings by acquiring specialised grocery retailers, this integration process is fraught with challenges.
Keemart cannot directly replicate its domestic supply chain operations abroad. The lack of effective collaboration across business units makes it difficult to achieve the same level of unified supply chain integration as in China. However, in terms of delivery networks, Keemart has achieved efficient integration with Keeta. Keemart directly utilises Keeta’s rider resources, reducing delivery costs by 30% and further improving delivery efficiency through order consolidation. Simultaneously, Keemart leverages Keeta’s user traffic by establishing entry points within the Keeta app, thereby reducing customer acquisition costs and avoiding high upfront marketing investments. Furthermore, Keemart and Keeta collaborate on market payments and promotional activities through a shared data platform and utilise user data analytics to understand product demand trends.
In November 2025, the average Keemart order value was between 80 and 100 riyals, equivalent to approximately $21-$27. The current monthly repeat purchase rate is below 30%, falling short of the 35-40% target. However, the data show a monthly upward trend, and it is expected to reach 35%. Each warehouse handles an average of about 400 orders per day, falling short of the expected 500-600 orders and below the break-even point of 500 orders. Still, Keemart’s total transaction value slightly exceeded expectations, with the actual average order value being 2 to 3 riyals higher than the previously estimated 85 riyals.
Keemart currently operates in only one country, but it plans to expand its business in the Middle East, targeting 10 cities, primarily focusing on large cities with populations exceeding one million in regions such as the UAE (e.g., Dubai) and Kuwait. Notably, Keemart has higher population size requirements for its target cities. In contrast, Keeta operates in cities with populations exceeding 200,000, while Keemart requires cities with populations over one million to begin operations. This differentiated market-entry standard reflects the characteristics of two distinct business models.
The geographical expansion will lengthen Keemart’s operational timeline, making profitability forecasting more complex. Furthermore, Keemart’s financial accounting model for overseas operations remains undetermined; it may adopt a large-regional approach, such as for the Saudi Arabia region, or it may be accounted for as a separate business unit. Given that Keemart is currently in a trial-and-exploration phase and overall business development is not yet ideal, it remains unclear when it will achieve profitability.
Cost structure of front-end warehouses
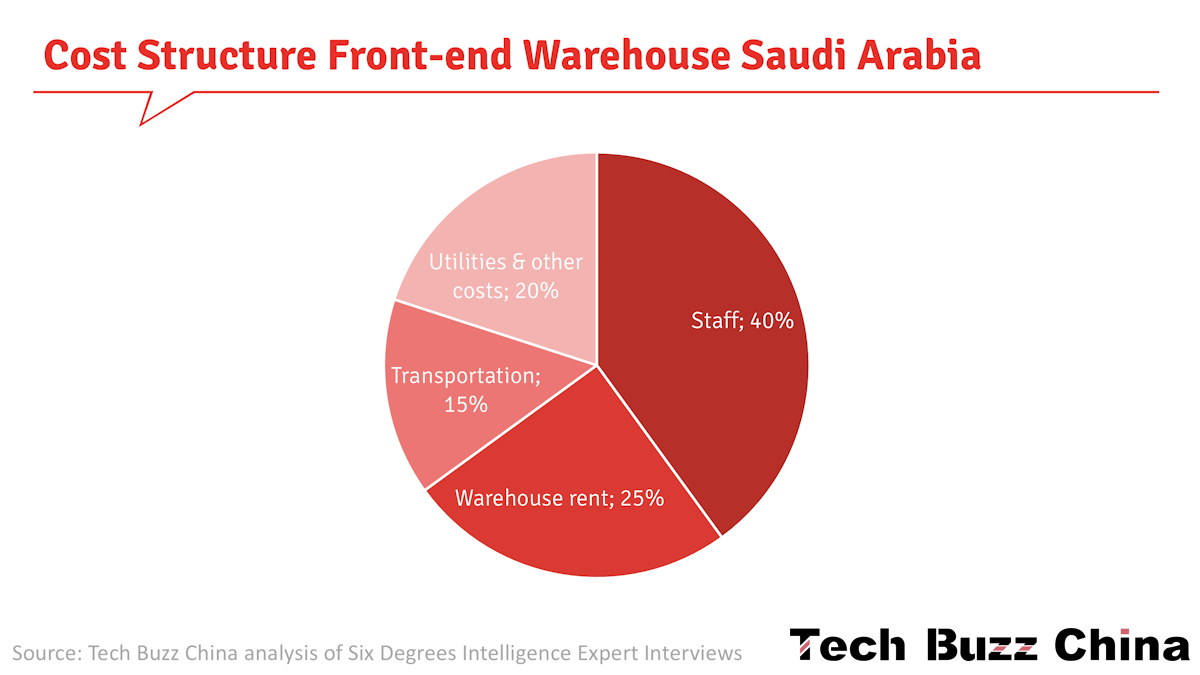
Operating a front-end warehouse in Saudi Arabia incurs monthly operating costs of up to $ 50,000, significantly higher than in the Chinese market. Operating costs mainly include employee salaries, rent, logistics and distribution fees, merchandise procurement costs, and other expenses such as electricity. Specifically, employee salaries account for 40% of total costs, amounting to approximately $ 20,000, which is 1.8 times higher than in China. This is primarily due to the higher salary standards set by Saudi Arabian law, which are approximately 1.5 to 2 times those in China.
Warehouse rental costs account for 25% of total expenses, approximately $12.500, 2 to 2.5 times higher than in China. For example, rents in Riyadh’s core business district are 2-2.5 times higher than in cities such as Beijing and Shanghai. Transportation costs account for 15%, 1.5-2 times higher than in China. Saudi Arabia’s extreme heat accelerates wear and tear on transport vehicles, further increasing delivery costs. Electricity consumption costs are approximately 1.5 times higher than in second-tier cities and 1.3 times higher than in first-tier cities in China. Despite Saudi Arabia being a major oil producer, rising electricity prices have driven costs for refrigeration, lighting, and other necessities to approximately 1.2 to 1.5 times those in China.
The financial recovery period for a single warehousing facility typically exceeds 12 months from investment to cost recovery, although this period can vary depending on actual operating conditions.
Challenges
Keemart faces several challenges in building its business in Saudi Arabia and other Gulf states.
The expansion of the fresh grocery retail business is not as rapid as that of food delivery services, primarily because local consumers prefer high-value bulk purchases for their families rather than the on-demand consumption model of convenience stores. Due to high local labour costs, delivery fees are typically around $1.50. Consumers are unwilling to pay high delivery fees for convenience store items priced at a few dollars, preferring to make bulk family purchases once or twice a week. Changing this consumption habit will take time.
Unlike the food delivery business, the front-end warehouse is an asset-heavy investment business. Procurement and fulfilment costs are the two major expenditures. Fulfilment costs include distribution, warehouse operating expenses, rent, and depreciation. Given that rents and other costs in Saudi Arabia are higher than in China, the cost of building warehouses overseas will be higher. [17]
In the Middle East, Meituan faces challenges from local competitors, including Nana, Rabbit, HungerStation’s HMarket, and Jahez, a same-city delivery platform. Most of these are locals with mature experience. For example, in Saudi Arabia, Jahez and Lugmety already operate self-operated grocery retail distribution businesses. [17] Ninja and Nana adopted a front-end warehouse model, covering categories such as fresh agricultural products, skincare products, and pet food. Ninja was ranked Top 1 in local food app downloads in 2024. Nana was founded in 2016 and innovatively launched the front-end warehouse model in Saudi Arabia, focusing on “delivery within 15 minutes”. [18]
Meituan has room for improvement in localisation, as evidenced by missteps during Ramadan in Saudi Arabia stemming from a lack of understanding of local consumer behaviour. In contrast, local platforms like Jahez have a deeper understanding of local culture and consumption habits. These local competitors excel at understanding consumer behaviour patterns, especially during special periods like Ramadan, and respond quickly to market changes, while Meituan experienced operational errors during this period.
Meituan still has room to improve its brand influence, particularly in Keemart’s market awareness, although Keeta performs relatively well in brand recognition.
Several other key factors should be considered in Keemart’s expansion strategy in the Middle East. First, the capital recovery period may be extended, with the specific recovery timeline yet to be determined. This presents a challenge in formulating an expansion plan. Keemart has significant business potential in Saudi Arabia, but given its asset-heavy operating model, it is expected to focus primarily on major metropolitan areas such as Riyadh, Dubai, and Doha rather than smaller cities.
Supply chain management is another significant challenge for Meituan. Due to the limited capabilities of local suppliers, Meituan has had to rely on China’s domestic supply chain system. Furthermore, Meituan’s initial strategy in the Saudi market was to promote both flash sales and food delivery services simultaneously; however, due to various factors, the food delivery launch was delayed.
Even more challenging is Meituan's difficulty in securing local strategic partners, as competitors have already signed exclusive agreements with some suppliers, resulting in Meituan’s procurement costs about 20% higher than competitors'. To address these challenges and enhance its competitiveness, Meituan launched a strategic project, “Little Elephant Goes Global,” focused on addressing key issues such as supply chain construction and expanding partnerships.
Last but not least, there currently are no in-store service products similar to Dianping (a popular Chinese review platform), but they may be developed in the future. The challenge lies in rebuilding the local user base and content system, a process that requires time. The local market has demand for advertising-driven traffic models that combine “maps, coupons, and payments.” Still, given the limited penetration of mobile payments, its business model is closer to Google Maps or Yelp than to a group-buying model characterised by a closed-loop transaction.
Which brings us to …
Dianping’s international expansion
In November 2025, it was reported that Dianping, Meituan's review platform, planned to expand further overseas, primarily to serve outbound Chinese tourists and the Chinese diaspora. Overseas restaurants on Dianping’s ‘Must-Eat List’ have already seen a significant increase in the number of Chinese visitors. But it’s not just Chinese they are after; Dianping has been launching multilingual versions in English, Korean, and other languages since the beginning of the year. [19]
Dianping played a crucial role in driving business to Meituan in China. In the long term, Dianping hopes to extend this influence to global users. If it can build the same level of credibility and influence overseas, Meituan’s potential in the international market may be even greater. [19]
“Information density” (name, category, coordinates, address, etc. of a Point of Interest in a geographic information system) is currently the highest priority for Dianping’s overseas business. The Dianping General Manager calls this an “extremely heavy, long-term, and complex (..) project.” As a benchmark, Dianping’s POI accuracy in mainland China is already high enough that, if a merchant is closed on a particular day, the platform detects the closure and updates the status within one hour. Only when the POI information is complete and accurate will users read and write reviews. And only then can Dianping proceed with ranking lists and other businesses, such as group buying. The ranking list has already been launched in Dubai. [19]
The overseas business team that Dianping established in June has grown to 50 people. 1.000 cities in almost all countries around the world are now available on Dianping, but it currently focuses on 100 cities that cover 95% of outbound Chinese tourists’ destinations. This builds on work already done in Southeast Asia before COVID. There, Dianping already helps people make decisions and provides services such as reservations and group bookings. Agents in various countries help organise information and even collaborate on group buying, marketing activities, and related initiatives. [19]
“In the future, we will further localise our rankings so that foreigners can also see them; this is something we are working hard on. (..) We aspire to become a global yellow pages directory that meets users’ information needs.” [19]
If this works out, Meituan might be able to solve the lack of a content system in the Middle East.

Source: Keeta LinkedIn
Drone delivery
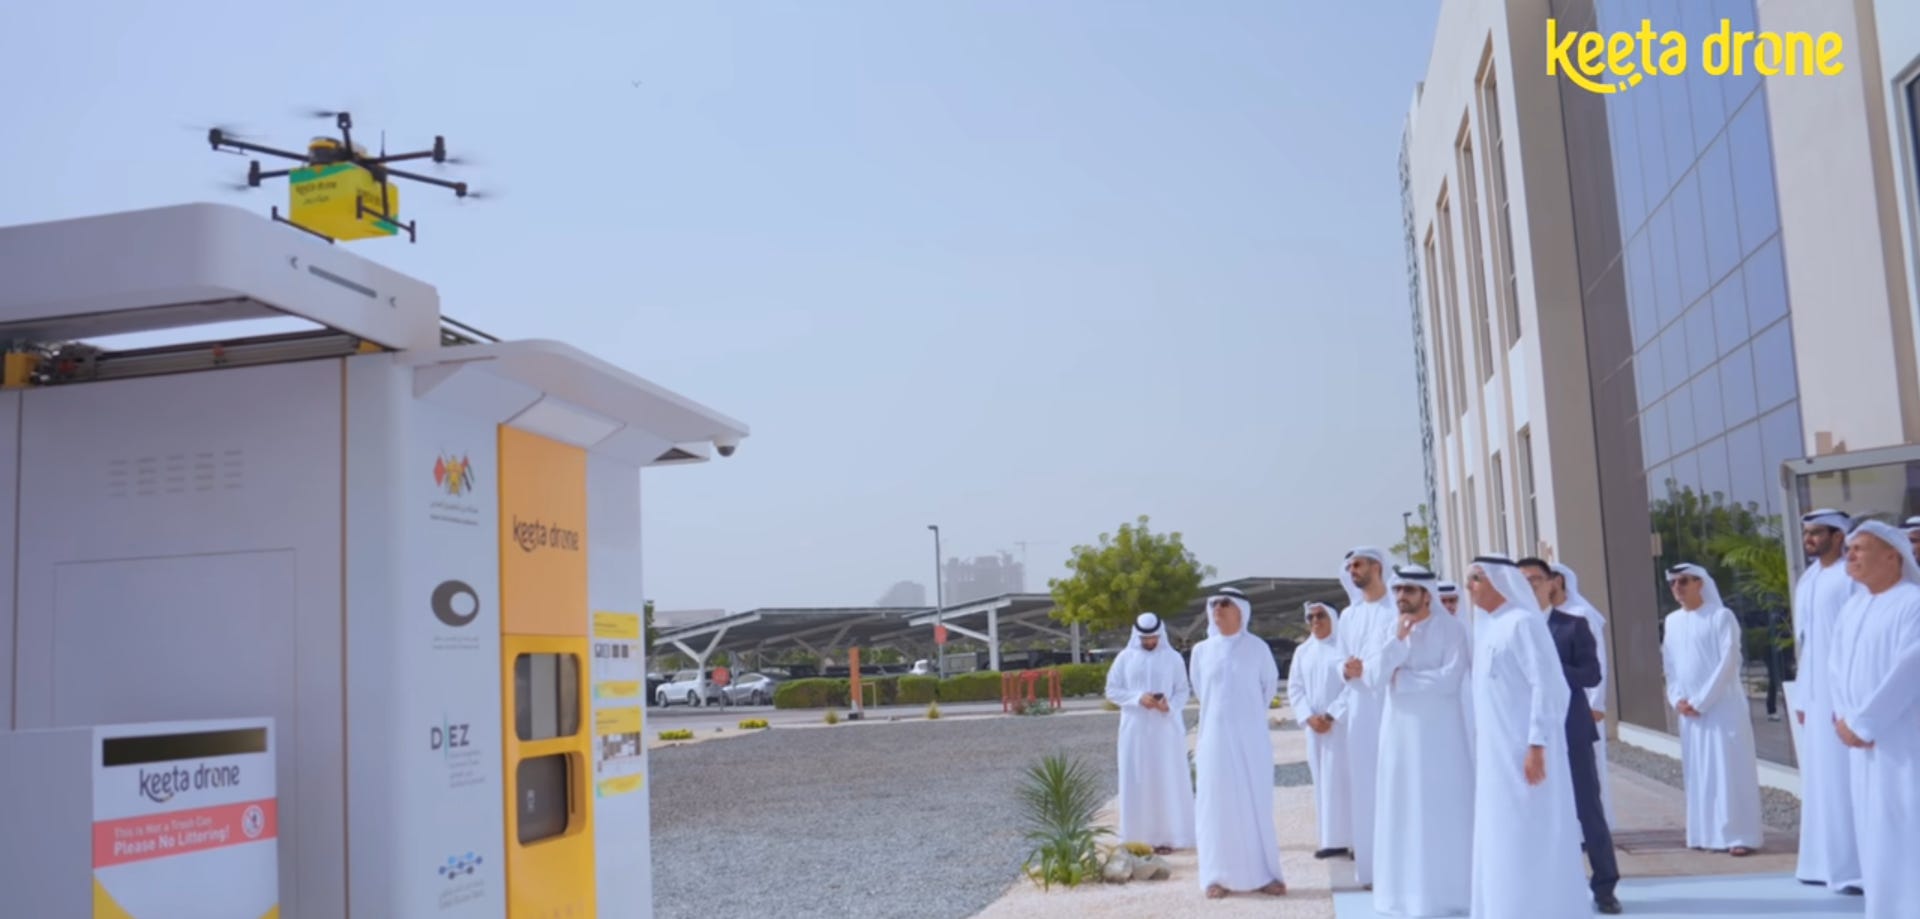
Meituan has made significant progress in automated delivery technology, particularly with Keeta’s successful implementation and outstanding performance in the Middle East. In December 2024, Meituan launched its drone business in its first overseas market, Dubai, under the name “Keeta Drone”. Its initial operational status is similar to third-party logistics: it has entered into partnerships with some restaurant chains to provide delivery services in specific areas of Dubai, but the coverage is limited, primarily to the RIT campus (Rochester Institute of Technology) and the DDP area (Dubai Digital Park). In addition, Keeta Drone was negotiating with local hospitals. It plans to expand into medical applications, such as drug delivery, in the future, gradually integrating catering, fresh food, medicine, and other categories for supply. [20]
Meituan had already conducted a drone delivery demonstration at the “Gitex Global 2023” event in October 2023. This was also the first time Dubai had allowed drones to take off in crowded areas. The Middle East was chosen because policy openness is critical to the drone business, and the local food delivery market must also have a solid foundation. Dubai’s commitment to building future cities and promoting the application of advanced technologies, such as drone delivery, is attractive to companies in related industries. Since the UAE is more open to the low-altitude economy than Saudi Arabia, Meituan started Keeta Drone there. [20]
Keeta Drone obtained the BVLOS drone delivery commercial operation qualification certificate issued by the Dubai Civil Aviation Authority on December 17 2024 - the first certificate issued in the region - which also means that Meituan officially has the qualifications to carry out commercial drone operations in the UAE. [20]
From the demand side, the weather in the Middle East is too hot, which will create poor conditions for manual delivery during the summer noon to afternoon, and takeout supply will also be limited. In addition, regional and road connectivity in Middle Eastern countries is relatively low, leaving more areas where drone delivery can be leveraged. Dubai has many artificial islands with many one-way roads in and out. It usually takes a long detour to reach two seemingly close points, and traffic congestion is also the norm. Drones may only need to cross a few hundred meters. [20]
The general process of drone delivery of takeout is as follows. After the deliveryman picks up the food in the store, he goes to the nearest take-off site to load it onto the drone. The drone then flies along the established route, lands at the community landing site, and unloads its cargo into the food collection cabinet at the airport. The user then scans the code to pick up the food. A similar process applies in Dubai, using an automated station that integrates take-off and landing and food storage. However, compared with manual home delivery, this option is less convenient. Meituan is exploring internal technical iterations and is highly likely to avoid relying on take-off and landing spots to cover more areas in the future. [20]
Source: Keeta LinkedIn
Meituan plans to increase the share of automated deliveries by 2027, aiming to raise it from 10% to 30% in overseas markets and to 20% in the domestic market. It firmly believes its AI-enabled unmanned delivery technology will help it gain greater recognition and investment in the capital markets. However, from a purely commercial perspective, the notion of drone delivery being universally adopted has been difficult to convince the market of, largely due to the high cost. Still, Meituan’s drone delivery costs have been declining year over year, and internal estimates suggest that in three to five years, drone delivery costs could reach a level comparable to road delivery. The ideal short-term target for Keeta Drone over 3 to 5 years is to cover more than 10% of Keeta’s delivery orders. [20]
In the long run, Keeta Drone needs to identify a viable path to commercialisation, but at this stage, the focus remains on identifying additional scenarios where drones offer advantages and on improving system stability and product adaptability. The advantage is that “labour costs in the Middle East are high, which is good for the drone business. From the perspective of gross profit turning positive, it may eventually be faster than in China.” [20]
Meituan’s resource investment is primarily focused on three core areas: supply chain, user traffic, and delivery execution. It places particular emphasis on accumulating training data for automated delivery technologies and researching and exploring future point-to-point delivery models. Ultimately, Meituan’s delivery execution system, integrating data collection capabilities and future drone applications, provides a solid foundation for developing related businesses.
Meanwhile, in June 2025, Keeta launched its first drone flight route in Hong Kong, delivering meals from McDonald’s, Pizza Hut, and other restaurant chains. [21]
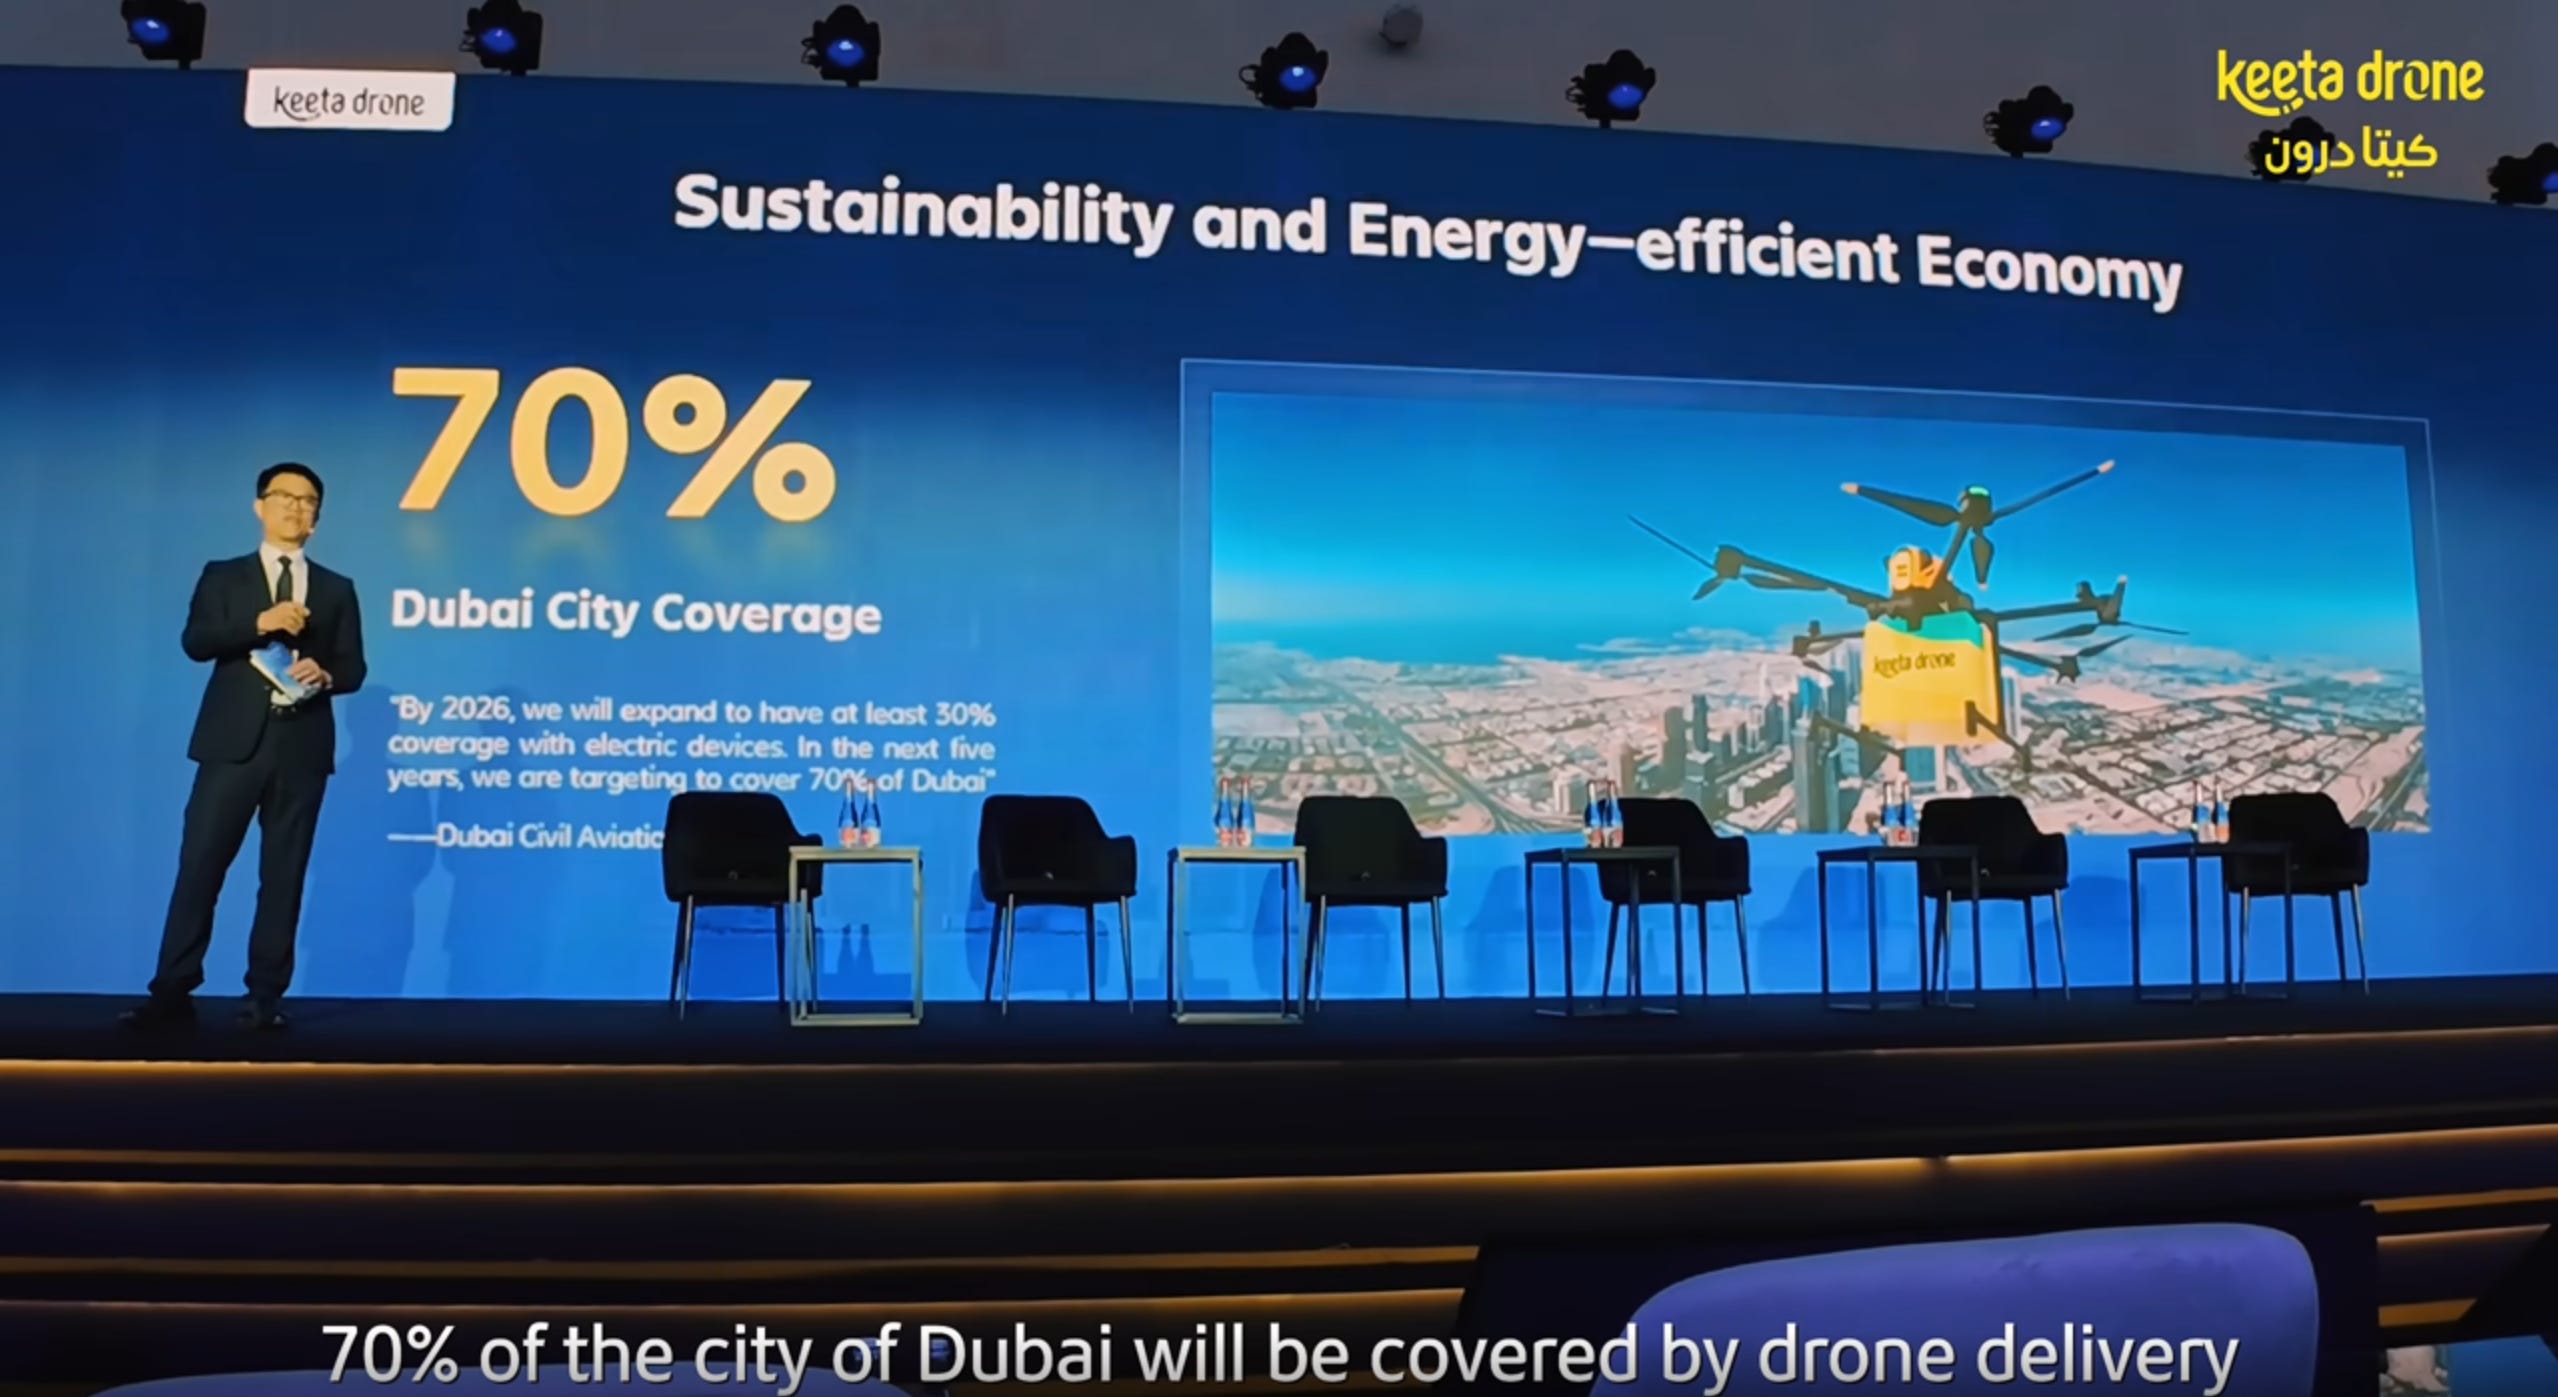
Dr Yinian Mao, President of Keeta Drone and VP of Meituan, at the Dubai Airshow. Source: Keeta LinkedIn.
Later this month, we will continue this story with a second report on Meituan’s expansion into Brazil. We will also explore how Meituan handles user and merchant acquisition, funding and localisation, and the outlook for profitability and further expansion. Stay tuned.
Key Takeaways and summary video
The key takeaways and the summary video below were created using Google Notebook.
Rapid Market Leadership: Within just one year, Keeta became the number one food delivery platform in Hong Kong by order volume and reached a top-two position in the Saudi Arabian market.
Strategic Market Selection: Meituan prioritises economically prosperous, mature markets with high growth potential, such as the Middle East and Europe, while avoiding less-developed regions to avoid the need for extensive market education.
Profitability Milestones: The Hong Kong business achieved profitability in 29 months, six months ahead of the company’s initial three-year target.
“Growth First” Strategy: To capture market share from incumbents, Keeta employs aggressive subsidies, including free shipping campaigns, vouchers, and heavily discounted single-person meals.
Saudi Arabia as a Primary Target: Saudi Arabia was selected for its large market size (estimated at $10 billion), high average order values, and favourable policy environment under its “Vision 2030“ strategy.
Ecosystem Expansion: Meituan is not just focusing on food; it is building a broader ecosystem by launching Keemart (front-end grocery warehouses) and expanding its review platform, Dianping, to international users.
Technological Advantages: The company leverages advanced delivery algorithms and has successfully launched commercial drone delivery operations in Dubai, enabling it to navigate challenges such as traffic congestion and extreme heat.
Localisation Challenges: Success in the Middle East requires navigating complex hurdles, including immature address systems, strict local labour policies, and shifts in consumption during religious periods like Ramadan.
High Operational Costs: Operating front-end warehouses in the Middle East is significantly more expensive than in China, with staff and rental costs in Saudi Arabia being 1.5 to 2.5 times higher.
Intense Competition: While Keeta has grown quickly, it faces established rivals like HungerStation and Talabat, which maintain dominant market shares in several Gulf countries.
To understand Meituan’s strategy, you can think of it as a grandmaster playing speed chess: they use highly calculated, aggressive opening moves (subsidies and algorithms) to seize the centre of the board (market share) as quickly as possible, even if it requires an initial sacrifice of pieces (short-term losses).
Sources
The information in this report is compiled from exclusive expert interviews within the Six Degrees Intelligence network, augmented with insights from the articles below.
Images by Tech Buzz China’s Ed Sander, unless stated otherwise. These images may not be reproduced without Tech Buzz China’s prior consent.
[1] 2023-12-15 36Kr [2] 2023-05-22 联商网 [3] 2025-03-10 Rest of World [4] 2025-08-31 36Kr [5] 2023-09-22 Pandaily [6] 2024-06-28 Tech星球 [7] 2024-10-16 36Kr [8] 2024-01-08 Technode [9] 2024-02-22 FBIC Group [10] 2025-03-05 Latepost [11] 2025-05-28 36Kr [12] 2024-08-01 FBCI Group [13] 2025-03-22 36Kr [14] 2025-11-29 36Kr [15] 2025-03-05 Technode [16] 2025-08-21 TechNode [17] 2025-06-10 Tech星球 [18] 2024-12-16 36Kr [19] 2025-11-12 36Kr [20] 2024-12-17 36Kr [21] 2025-06-06 Yicai